potentialwww.pu811.com
wwW.PU811.Com 时间:2021-04-09 阅读:()
www.
pwc.
comCOSOChangesandtheimpactonICFRApresentationtothePugetSoundChapteroftheIIAJanuary14,2014PwCAgendaIntroductionsCurrentTrendsImpactingSOXCOSO–What'sChangingWhat'sNotDeeperDriveonSelectedPrinciplesTransitioningICFRtothe2013FrameworkPCAOBActionsImpactingSOXManageCosts,DeliverValuefromSOXQuestions2January14,2014PwCCurrenttrendsimpactingSOX3January14,2014COSOUpdateDrivingFY'14SOXChangesPCAOBActionsManageCosts,DeliverValuePwCCOSO'sInternalControl-IntegratedFramework(2013)4January14,2014PwCWhyupdate1992frameworkDostakeholdersunderstandrequirementsofeffectiveinternalcontrol5January14,2014ChangesinthebusinessenvironmentChangesinsidethebusinessLackofclarityLackofunderstandingSource-COSO'ssurveyofusersandstakeholders,worldwide–JanuarytoSeptember20110%50%100%ControlActivitiesMonitoringControlEnvironmentInformation&…RiskAssessmentDifficulttointerpretSomewhatdifficulttointerpretModeratelyeasytointerpretGenerallyeasytointerpretEasytointerpretOnly50%thoughtitwasgenerallyeasytointerpretPwC2013Frameworkpreservescorestrengthsembeddedin1992Framework6January14,2014UpdatedCOSOCubeWhatisNotfundamentallychanging.
.
.
CoredefinitionofinternalcontrolThreecategoriesofobjectivesandfivecomponentsofinternalcontrolEachofthefivecomponentsofinternalcontrolarerequiredforeffectiveinternalcontrolImportantroleofjudgmentindesigning,implementingandconductinginternalcontrol,andinassessingitseffectivenessEntityStructureComponentsRiskAssessmentControlEnvironmentControlActivitiesMonitoringActivitiesInformationandCommunicationPwC2013Frameworkarticulatesprinciplesandpointsoffocus7January14,20142013COSOCube17PrinciplesPointsoffocusControls5ComponentsPointsoffocusdescribeimportantcharacteristicsofprinciplesPrinciplesarticulatefundamentalconceptsofcomponentsComponentsandPrinciplesarerequirementsforaneffectivesystemofinternalcontrolPointsofFocusandControlsaresubjecttomanagementjudgmentLegendRiskAssessmentControlEnvironmentControlActivitiesMonitoringActivitiesInformationandCommunicationPwC2013Frameworkarticulatesseventeenprinciplesforeffectiveinternalcontrol8January14,2014ControlEnvironment1.
Demonstratescommitmenttointegrityandethicalvalues2.
Exercisesoversightresponsibility3.
Establishesstructure,authorityandresponsibility4.
Demonstratescommitmenttocompetence5.
EnforcesaccountabilityRiskAssessment6.
Specifiessuitableobjectives7.
Identifiesandanalyzesrisk8.
Assessesfraudrisk9.
IdentifiesandanalyzessignificantchangeControlActivities10.
Selectsanddevelopscontrolactivities11.
Selectsanddevelopsgeneralcontrolsovertechnology12.
DeploysthroughpoliciesandproceduresInformation&Communication13.
Usesrelevantinformation14.
Communicatesinternally15.
CommunicatesexternallyMonitoringActivities16.
Conductsongoingand/orseparateevaluations17.
EvaluatesandcommunicatesdeficienciesPwC2013FrameworkclarifiesrequirementsforaneffectivesystemofinternalcontrolComponentsarepresentandfunctioningifeachrelevantprinciplesisdeterminedtobepresentandfunctioning(e.
g.
,nomaterialweaknessexists)Relevantprinciplesarepresentandfunctioningifpersuasiveevidenceexiststhatcontrolsareselected,developedanddeployedtoeffectthemComponentsoperatetogetherwhen:ComponentsarepresentandfunctioningInternalcontroldeficienciesaggregatedacrosscomponentsdonotresultinthedeterminationthatoneormorematerialweaknessexist9January14,2014Aneffectivesystemofinternalcontrolrequires:EachofthefivecomponentsofinternalcontrolandrelevantprinciplesispresentandfunctioningThefivecomponentsareoperatingtogetherinanintegratedmannerPwCCOSOprinciples–Adeeperdive10January14,2014PwC2013FrameworkandICFR–PrinciplesRelevantprinciplesarepresentandfunctioningifpersuasiveevidenceexiststhatcontrolsareselected,developedanddeployedtoeffectthemWhatcompaniesshoulddo:Documenthowthedesignofexistingcontrolsmapagainstthe17principles.
Remedypotentialdesigngapswhenexistingcontrolsarenotfullyadequate.
Testtheoperatingeffectivenessofanynewcontrolscomingintoscope11January14,2014PwC2013Frameworkdescribespointsoffocusforeachprinciple,e.
g.
12January14,2014Principle1DemonstratesCommitmenttoIntegrity…Principle2ExercisesOversightResponsibilityPrinciple3EstablishesStructuresAuthority,…ComponentControlEnvironmentSetsthetoneatthetopEstablishesstandardsofconductEvaluatesadherencetostandardsofconductAddressesdeviationsinatimelymannerEstablishesoversightresponsibilityAppliesrelevantexpertiseOperateindependentlyProvidesoversightforthesystemofinternalcontrolConsidersallstructuresoftheentityEstablishesreportinglinesDefines,assignsandlimitsauthoritiesandresponsibilitiesPrinciple4DemonstratesCommitmenttoCompetenceEstablishespoliciesandpracticesEvaluatescompetenceandaddressesshortcomingsAttracts,develops,andretainsindividualsPlansandpreparesforsuccessionPrinciplesPointsofFocusPwCPrinciplesandPointsofFocus,adeeperlook13January14,2014ComponentControlEnvironmentEstablishespoliciesandpracticesEvaluatescompetenceandaddressesshortcomingsAttracts,develops,andretainsindividualsPlansandpreparesforsuccessionPrinciple4DemonstratesCommitmenttoCompetenceTheorganizationdemonstratesacommitmenttoattract,develop,andretaincompetentindividualsinalignmentwithobjectives.
IndividualperformanceplansdefineexpectationsregardingICAllaccountingstaffattendannualupdatetrainingofnewaccountingpronouncementsControlExamplesPrinciplesPointsofFocusAnorganizationwithcomplexrevenueaccountingfailstomaintainadequatelytrainedCPAstooverseerevenueaccounting.
DeficiencyExamplesPwCPointsoffocusdescribeimportantcharacteristicsoftheprinciples,forexample…14January14,2014Principle6SpecifiessuitableobjectivesPrinciple7IdentifiesandanalysesriskPrinciple8AssessesfraudriskComponentRiskAssessmentComplieswithapplicableaccountingstandardsConsidersmaterialityReflectsentityactivitiesIncludesentity,division,operatingunit,andfunctionsAnalyzesinternal/externalfactorsInvolvesappropriatelevelofmanagementEstimatessignificanceofrisksidentifiedDetermineshowtorespondtorisksConsidersvarioustypesoffraudAssessesincentiveandpressuresAssessesopportunitiesAssessesattitudesandrationalizationsPrinciple9IdentifiesandanalyzessignificantchangeAssesseschangesinexternalenvironmentAssesseschangesinbusinessmodelAssesseschangesinleadershipPrinciplesPointsofFocusPwCPointsoffocusdescribeimportantcharacteristicsoftheprinciples,forexample…15January14,2014ComponentRiskAssessmentPointsofFocusPrinciple9:IdentifiesandAnalysesSignificantChangeTheorganizationidentifiesandassesseschangesthatcouldsignificantlyimpactthesystemofinternalcontrol.
PrinciplesAssesseschangesinexternalenvironmentAssesseschangesinbusinessmodelAssesseschangesinleadershipRiskassessmentsarerequiredforanysignificantchange,suchas:-InternationalExposure-SignificantAcquisitonCreateaninternalcontrolplanforanyexecutivetransitionControlExamplesThecompanyfailedtoupdatetheriskassessmentforchangesarisingfromtheChinaacquisition.
DeficiencyExamplesPwCTransitioningICFRto2013framework16January14,2014PwCTransitioningICFRto2013FrameworkCOSOdecidedtosupersedethe1992Frameworkattheendofthetransitionperiod(i.
e.
,December15,2014)"SECstaffplanstomonitorthetransitionforissuersusingthe1992frameworktoevaluatewhetherandifanystafforCommissionactionsbecomenecessaryorappropriateinthefuture.
However,atthistime,I'llsimplyreferusersoftheCOSOframeworktothestatementsCOSOhasmadeabouttheirnewframeworkandtheirthoughtsabouttransition.
"(PaulBeswick,S.
E.
C.
ChiefAccountant)TheSECstaffindicatedmorerecentlythatthelongerissuerscontinuetousethe1992framework,themorelikelytheyaretoreceivequestionsfromthestaffaboutwhethertheissuer'suseofthe1992frameworksatisfiestheSEC'srequirementtouseasuitable,recognizedframework,particularlyafterDecember15,2014whenCOSOwillconsiderthe1992frameworktohavebeensupersededbythe2013framework.
(CenterforAuditQuality'sSECRegulationsCommittee)17January14,2014PwCA404transitionplan(example)18January14,2014Four-phasesKeyActionsPhase1:EducateandCommunicateReview2013FrameworkandillustrativetoolsConducttrainingappropriateforboard/committeemembers,seniormanagement,managers,etc.
Developunderstandingofwhereprinciplesarerelevantattheentity(i.
e.
,corporate)andsubunits(divisions,subsidiaries,operatingunitsandfunctionallevels)Phase2:ConductPreliminaryAssessmentMap17principles(consideringpointsoffocus)toentitylevelcontrols(ELCs)ConsiderwhetherdifferencesincontrolsexistatsubunitsIdentifyanysignificant"gaps"indesignorSOXdocumentationofcontrols(i.
e.
,assesswhethereachcomponentofinternalcontrolandprincipleis"present")Phase3:CompleteAssessment&DevelopActionPlanPerformcomprehensiveassessmentandassesstheoperatingeffectivenessofcontrols(i.
e.
,assesswhethereachcomponentofinternalcontrolandprincipleis"functioning")AssessseverityofanyinternalcontroldeficienciesIdentifychangesincontrolsorSOXdocumentationnecessarytoremediatedeficienciesPhase4:ExecuteActionPlanRemediateinternalcontroldeficienciesofSOXdocumentation,asneededPwCPotentialimpactonICFRReactionsandresponseswilldifferdependingoncircumstancesIf1992FrameworkhasbeenthoroughlyappliedtocurrentICFR,thetransitionshouldnotresultinsignificantchangesorincrementaleffortPreliminaryassessment(i.
e.
,mappingprinciples,consideringpointsoffocus,tocontrols)mayreveal"gaps"indesignordocumentationofsomecontrols-Design—Controlsarenotdesignedtodemonstrateaprincipleispresent-Documentation—Controlsassociatedwiththeprincipleexist,buttheyarenotincludedintheSOXinternalcontroldocumentation19January14,2014PwCPotentialimpactonICFRFocusondesignofindirectentitylevelcontrols(ELCs)thataffectthe14principlesassociatedwiththe"softer"componentsofinternalcontrol.
IndirectELCshaveanimportant,butindirect,effectonthelikelihoodthatamisstatementwillbedetectedorpreventedonatimelybasis.
NoimpactexpectedondesignofdirectELCsandtransactionlevelcontrols(e.
g.
,threewaymatch,cashreconciliation)relatingtoControlActivities20January14,2014PwCPotentialimpactonICFRELCsoperatethroughouttheentireorganizationandoftenhaveapervasiveimpactoncontrols.
Forexample,thedesignofanindirectELCfocusedonassessingfinancialreportingriskscanbeconductedatthecorporateleveltoassessrisksrelatingtoallcomponentsoftheentity(i.
e.
,subunitlocations)oratindividualcomponentsDeterminingwhetheraprincipleispresentisamatterofmanagementjudgment.
AssessingthedesignofELCsinclude:-Component(s)oftheentitycoveredbythecontrolbeingevaluated-Objectiveofthecontrol-Whoperformsthecontrolwithnecessaryauthorityandcompetence-Frequencyofthecontrol'soperation-Specificproceduresthatareperformedtomeetthestatedobjective,includinganyinformationusedintheoperationofthecontrol21January14,2014PwCPotentialimpactonICFRBytakingafreshlookatthedesignofindirectELCs,managementmayidentifyopportunitiestore-designcontrolstoenhanceeffectivenessorefficiency22January14,2014PwCPotentialimpactonICFREvaluationofthethreeprinciplesrelatedtotheControlActivitiescomponentshouldbefocusedontheprocessforselecting,developinganddeployingcontrolactivitiesratherthanthedetailedcontrolactivitiesthemselves.
-Therefore,transitioningtothe2013Frameworkwillnotresultinanychangestoacompany'sriskandcontrolmatricesrelatingtotransactioncontrols(e.
g.
,threewaymatch,cashreconciliations,etc.
).
Themappingofprinciplestocontrolswillultimatelysupportthecompany'sdesignofthe"soft"componentsofinternalcontroloverfinancialreportinginaccordancewiththe2013Framework23January14,2014PwCPCAOBactionsimpactingSOX24January14,2014PwCPCAOBactionsimpactingSOXIncreasedfocusbyPCOABoninternalcontrolaspectsoftheIntegratedauditleadingtoincreasedPCAOBauditfindingsrelatedtointernalcontrol.
DocumentedininspectionreportsandtheActionAlert,datedOctober24th,2013.
DrivingchangesinexternalauditapproachtoICFR,increasedlevelsofdocumentation,changestocontroldesignandrequestsforadditionalevidence.
TheimpactonSOXteamsinsomesituationscanbesignificant.
25January14,2014PwCPCAOBareasofobservationSomeObservationsArecontrolsproperlydesignedandalignedtorisksTestingofmanagementreviewcontrolsEvidenceoversystemgenerateddataandreportsUseofworkofothersControlsover:-JournalEntries-Estimates,-Uniquetransactions,-Incometaxes26ImpacttoSOXTeamsIncreasedocumentationofend-to-endprocess,qualificationofcontrolperformers,andSODIncreaserigorofmanagementreviewcontrolsanddocumentationofpropercontrolexecution.
Enhancecontrolsoverspreadsheetsandotherend-userapplications.
Assistancewithtestingofkeyreports.
Criticalassessmentofcompetenceandobjectivity.
Lessrelianceonmanagementtesting.
Re-designofmanualandautomatedcontrolsoversensitiveareas.
January14,2014PwCHolisticApproachtoManageCosts,DeliverValue27ProcessLeanprocessframeworkappliedtocontrols,relateddocumentationandprojectmanagementprocessestoalignwithriskandstreamlineunnecessaryactivitiesIdentifyingcapabilitiestouseariskbasedtestingapproachtofocuseffortsonareaswithhighestriskoferrorandmisstatement.
StrategyEnsuresstakeholderalignmentaroundSOXprogramobjectivesandchangegoalsStructureCapturessynergiesbetweenSOXprogramsandexternalauditstodrivehighlevelsofexternalauditreliance.
PeopleUnderstandthetrainingandcontrolsknowledgeofthoseemployeesperformingkeycontrolsDeterminethemostcost-effectiveresourcesperformingworkwithlimitedvalue.
UnderstandtheexperienceandbackgroundofprogrammanagementrunningtheSOXprogram.
TechnologyEvaluateGRCplatforms,todeterminethattheyenableefficientworkflowsuchashand-offs,approvalsandmanagementreportingAutomatedcontrolsandcontinuousmonitoringareusedwherepossible,suchassegregationofduties,interfacebalancing,reconciliationsandtransactionmonitoring.
RequirementsMonitoringProgramManagementStrategyStakeholderAlignmentStructureSynergisticPeopleTrainedCostEffectiveExperiencedProcessLeanRiskBasedStreamlinedTechnologyAutomatedContinuousWorkflowQualityCompetent&ObjectiveJanuary14,2014PwCQuestions28January14,2014Thankyou.
.
.
2014PricewaterhouseCoopersLLP.
Allrightsreserved.
PwCreferstotheUnitedStatesmemberfirm,andmaysometimesrefertothePwCnetwork.
Eachmemberfirmisaseparatelegalentity.
Pleaseseewww.
pwc.
com/structureforfurtherdetails.
pwc.
comCOSOChangesandtheimpactonICFRApresentationtothePugetSoundChapteroftheIIAJanuary14,2014PwCAgendaIntroductionsCurrentTrendsImpactingSOXCOSO–What'sChangingWhat'sNotDeeperDriveonSelectedPrinciplesTransitioningICFRtothe2013FrameworkPCAOBActionsImpactingSOXManageCosts,DeliverValuefromSOXQuestions2January14,2014PwCCurrenttrendsimpactingSOX3January14,2014COSOUpdateDrivingFY'14SOXChangesPCAOBActionsManageCosts,DeliverValuePwCCOSO'sInternalControl-IntegratedFramework(2013)4January14,2014PwCWhyupdate1992frameworkDostakeholdersunderstandrequirementsofeffectiveinternalcontrol5January14,2014ChangesinthebusinessenvironmentChangesinsidethebusinessLackofclarityLackofunderstandingSource-COSO'ssurveyofusersandstakeholders,worldwide–JanuarytoSeptember20110%50%100%ControlActivitiesMonitoringControlEnvironmentInformation&…RiskAssessmentDifficulttointerpretSomewhatdifficulttointerpretModeratelyeasytointerpretGenerallyeasytointerpretEasytointerpretOnly50%thoughtitwasgenerallyeasytointerpretPwC2013Frameworkpreservescorestrengthsembeddedin1992Framework6January14,2014UpdatedCOSOCubeWhatisNotfundamentallychanging.
.
.
CoredefinitionofinternalcontrolThreecategoriesofobjectivesandfivecomponentsofinternalcontrolEachofthefivecomponentsofinternalcontrolarerequiredforeffectiveinternalcontrolImportantroleofjudgmentindesigning,implementingandconductinginternalcontrol,andinassessingitseffectivenessEntityStructureComponentsRiskAssessmentControlEnvironmentControlActivitiesMonitoringActivitiesInformationandCommunicationPwC2013Frameworkarticulatesprinciplesandpointsoffocus7January14,20142013COSOCube17PrinciplesPointsoffocusControls5ComponentsPointsoffocusdescribeimportantcharacteristicsofprinciplesPrinciplesarticulatefundamentalconceptsofcomponentsComponentsandPrinciplesarerequirementsforaneffectivesystemofinternalcontrolPointsofFocusandControlsaresubjecttomanagementjudgmentLegendRiskAssessmentControlEnvironmentControlActivitiesMonitoringActivitiesInformationandCommunicationPwC2013Frameworkarticulatesseventeenprinciplesforeffectiveinternalcontrol8January14,2014ControlEnvironment1.
Demonstratescommitmenttointegrityandethicalvalues2.
Exercisesoversightresponsibility3.
Establishesstructure,authorityandresponsibility4.
Demonstratescommitmenttocompetence5.
EnforcesaccountabilityRiskAssessment6.
Specifiessuitableobjectives7.
Identifiesandanalyzesrisk8.
Assessesfraudrisk9.
IdentifiesandanalyzessignificantchangeControlActivities10.
Selectsanddevelopscontrolactivities11.
Selectsanddevelopsgeneralcontrolsovertechnology12.
DeploysthroughpoliciesandproceduresInformation&Communication13.
Usesrelevantinformation14.
Communicatesinternally15.
CommunicatesexternallyMonitoringActivities16.
Conductsongoingand/orseparateevaluations17.
EvaluatesandcommunicatesdeficienciesPwC2013FrameworkclarifiesrequirementsforaneffectivesystemofinternalcontrolComponentsarepresentandfunctioningifeachrelevantprinciplesisdeterminedtobepresentandfunctioning(e.
g.
,nomaterialweaknessexists)Relevantprinciplesarepresentandfunctioningifpersuasiveevidenceexiststhatcontrolsareselected,developedanddeployedtoeffectthemComponentsoperatetogetherwhen:ComponentsarepresentandfunctioningInternalcontroldeficienciesaggregatedacrosscomponentsdonotresultinthedeterminationthatoneormorematerialweaknessexist9January14,2014Aneffectivesystemofinternalcontrolrequires:EachofthefivecomponentsofinternalcontrolandrelevantprinciplesispresentandfunctioningThefivecomponentsareoperatingtogetherinanintegratedmannerPwCCOSOprinciples–Adeeperdive10January14,2014PwC2013FrameworkandICFR–PrinciplesRelevantprinciplesarepresentandfunctioningifpersuasiveevidenceexiststhatcontrolsareselected,developedanddeployedtoeffectthemWhatcompaniesshoulddo:Documenthowthedesignofexistingcontrolsmapagainstthe17principles.
Remedypotentialdesigngapswhenexistingcontrolsarenotfullyadequate.
Testtheoperatingeffectivenessofanynewcontrolscomingintoscope11January14,2014PwC2013Frameworkdescribespointsoffocusforeachprinciple,e.
g.
12January14,2014Principle1DemonstratesCommitmenttoIntegrity…Principle2ExercisesOversightResponsibilityPrinciple3EstablishesStructuresAuthority,…ComponentControlEnvironmentSetsthetoneatthetopEstablishesstandardsofconductEvaluatesadherencetostandardsofconductAddressesdeviationsinatimelymannerEstablishesoversightresponsibilityAppliesrelevantexpertiseOperateindependentlyProvidesoversightforthesystemofinternalcontrolConsidersallstructuresoftheentityEstablishesreportinglinesDefines,assignsandlimitsauthoritiesandresponsibilitiesPrinciple4DemonstratesCommitmenttoCompetenceEstablishespoliciesandpracticesEvaluatescompetenceandaddressesshortcomingsAttracts,develops,andretainsindividualsPlansandpreparesforsuccessionPrinciplesPointsofFocusPwCPrinciplesandPointsofFocus,adeeperlook13January14,2014ComponentControlEnvironmentEstablishespoliciesandpracticesEvaluatescompetenceandaddressesshortcomingsAttracts,develops,andretainsindividualsPlansandpreparesforsuccessionPrinciple4DemonstratesCommitmenttoCompetenceTheorganizationdemonstratesacommitmenttoattract,develop,andretaincompetentindividualsinalignmentwithobjectives.
IndividualperformanceplansdefineexpectationsregardingICAllaccountingstaffattendannualupdatetrainingofnewaccountingpronouncementsControlExamplesPrinciplesPointsofFocusAnorganizationwithcomplexrevenueaccountingfailstomaintainadequatelytrainedCPAstooverseerevenueaccounting.
DeficiencyExamplesPwCPointsoffocusdescribeimportantcharacteristicsoftheprinciples,forexample…14January14,2014Principle6SpecifiessuitableobjectivesPrinciple7IdentifiesandanalysesriskPrinciple8AssessesfraudriskComponentRiskAssessmentComplieswithapplicableaccountingstandardsConsidersmaterialityReflectsentityactivitiesIncludesentity,division,operatingunit,andfunctionsAnalyzesinternal/externalfactorsInvolvesappropriatelevelofmanagementEstimatessignificanceofrisksidentifiedDetermineshowtorespondtorisksConsidersvarioustypesoffraudAssessesincentiveandpressuresAssessesopportunitiesAssessesattitudesandrationalizationsPrinciple9IdentifiesandanalyzessignificantchangeAssesseschangesinexternalenvironmentAssesseschangesinbusinessmodelAssesseschangesinleadershipPrinciplesPointsofFocusPwCPointsoffocusdescribeimportantcharacteristicsoftheprinciples,forexample…15January14,2014ComponentRiskAssessmentPointsofFocusPrinciple9:IdentifiesandAnalysesSignificantChangeTheorganizationidentifiesandassesseschangesthatcouldsignificantlyimpactthesystemofinternalcontrol.
PrinciplesAssesseschangesinexternalenvironmentAssesseschangesinbusinessmodelAssesseschangesinleadershipRiskassessmentsarerequiredforanysignificantchange,suchas:-InternationalExposure-SignificantAcquisitonCreateaninternalcontrolplanforanyexecutivetransitionControlExamplesThecompanyfailedtoupdatetheriskassessmentforchangesarisingfromtheChinaacquisition.
DeficiencyExamplesPwCTransitioningICFRto2013framework16January14,2014PwCTransitioningICFRto2013FrameworkCOSOdecidedtosupersedethe1992Frameworkattheendofthetransitionperiod(i.
e.
,December15,2014)"SECstaffplanstomonitorthetransitionforissuersusingthe1992frameworktoevaluatewhetherandifanystafforCommissionactionsbecomenecessaryorappropriateinthefuture.
However,atthistime,I'llsimplyreferusersoftheCOSOframeworktothestatementsCOSOhasmadeabouttheirnewframeworkandtheirthoughtsabouttransition.
"(PaulBeswick,S.
E.
C.
ChiefAccountant)TheSECstaffindicatedmorerecentlythatthelongerissuerscontinuetousethe1992framework,themorelikelytheyaretoreceivequestionsfromthestaffaboutwhethertheissuer'suseofthe1992frameworksatisfiestheSEC'srequirementtouseasuitable,recognizedframework,particularlyafterDecember15,2014whenCOSOwillconsiderthe1992frameworktohavebeensupersededbythe2013framework.
(CenterforAuditQuality'sSECRegulationsCommittee)17January14,2014PwCA404transitionplan(example)18January14,2014Four-phasesKeyActionsPhase1:EducateandCommunicateReview2013FrameworkandillustrativetoolsConducttrainingappropriateforboard/committeemembers,seniormanagement,managers,etc.
Developunderstandingofwhereprinciplesarerelevantattheentity(i.
e.
,corporate)andsubunits(divisions,subsidiaries,operatingunitsandfunctionallevels)Phase2:ConductPreliminaryAssessmentMap17principles(consideringpointsoffocus)toentitylevelcontrols(ELCs)ConsiderwhetherdifferencesincontrolsexistatsubunitsIdentifyanysignificant"gaps"indesignorSOXdocumentationofcontrols(i.
e.
,assesswhethereachcomponentofinternalcontrolandprincipleis"present")Phase3:CompleteAssessment&DevelopActionPlanPerformcomprehensiveassessmentandassesstheoperatingeffectivenessofcontrols(i.
e.
,assesswhethereachcomponentofinternalcontrolandprincipleis"functioning")AssessseverityofanyinternalcontroldeficienciesIdentifychangesincontrolsorSOXdocumentationnecessarytoremediatedeficienciesPhase4:ExecuteActionPlanRemediateinternalcontroldeficienciesofSOXdocumentation,asneededPwCPotentialimpactonICFRReactionsandresponseswilldifferdependingoncircumstancesIf1992FrameworkhasbeenthoroughlyappliedtocurrentICFR,thetransitionshouldnotresultinsignificantchangesorincrementaleffortPreliminaryassessment(i.
e.
,mappingprinciples,consideringpointsoffocus,tocontrols)mayreveal"gaps"indesignordocumentationofsomecontrols-Design—Controlsarenotdesignedtodemonstrateaprincipleispresent-Documentation—Controlsassociatedwiththeprincipleexist,buttheyarenotincludedintheSOXinternalcontroldocumentation19January14,2014PwCPotentialimpactonICFRFocusondesignofindirectentitylevelcontrols(ELCs)thataffectthe14principlesassociatedwiththe"softer"componentsofinternalcontrol.
IndirectELCshaveanimportant,butindirect,effectonthelikelihoodthatamisstatementwillbedetectedorpreventedonatimelybasis.
NoimpactexpectedondesignofdirectELCsandtransactionlevelcontrols(e.
g.
,threewaymatch,cashreconciliation)relatingtoControlActivities20January14,2014PwCPotentialimpactonICFRELCsoperatethroughouttheentireorganizationandoftenhaveapervasiveimpactoncontrols.
Forexample,thedesignofanindirectELCfocusedonassessingfinancialreportingriskscanbeconductedatthecorporateleveltoassessrisksrelatingtoallcomponentsoftheentity(i.
e.
,subunitlocations)oratindividualcomponentsDeterminingwhetheraprincipleispresentisamatterofmanagementjudgment.
AssessingthedesignofELCsinclude:-Component(s)oftheentitycoveredbythecontrolbeingevaluated-Objectiveofthecontrol-Whoperformsthecontrolwithnecessaryauthorityandcompetence-Frequencyofthecontrol'soperation-Specificproceduresthatareperformedtomeetthestatedobjective,includinganyinformationusedintheoperationofthecontrol21January14,2014PwCPotentialimpactonICFRBytakingafreshlookatthedesignofindirectELCs,managementmayidentifyopportunitiestore-designcontrolstoenhanceeffectivenessorefficiency22January14,2014PwCPotentialimpactonICFREvaluationofthethreeprinciplesrelatedtotheControlActivitiescomponentshouldbefocusedontheprocessforselecting,developinganddeployingcontrolactivitiesratherthanthedetailedcontrolactivitiesthemselves.
-Therefore,transitioningtothe2013Frameworkwillnotresultinanychangestoacompany'sriskandcontrolmatricesrelatingtotransactioncontrols(e.
g.
,threewaymatch,cashreconciliations,etc.
).
Themappingofprinciplestocontrolswillultimatelysupportthecompany'sdesignofthe"soft"componentsofinternalcontroloverfinancialreportinginaccordancewiththe2013Framework23January14,2014PwCPCAOBactionsimpactingSOX24January14,2014PwCPCAOBactionsimpactingSOXIncreasedfocusbyPCOABoninternalcontrolaspectsoftheIntegratedauditleadingtoincreasedPCAOBauditfindingsrelatedtointernalcontrol.
DocumentedininspectionreportsandtheActionAlert,datedOctober24th,2013.
DrivingchangesinexternalauditapproachtoICFR,increasedlevelsofdocumentation,changestocontroldesignandrequestsforadditionalevidence.
TheimpactonSOXteamsinsomesituationscanbesignificant.
25January14,2014PwCPCAOBareasofobservationSomeObservationsArecontrolsproperlydesignedandalignedtorisksTestingofmanagementreviewcontrolsEvidenceoversystemgenerateddataandreportsUseofworkofothersControlsover:-JournalEntries-Estimates,-Uniquetransactions,-Incometaxes26ImpacttoSOXTeamsIncreasedocumentationofend-to-endprocess,qualificationofcontrolperformers,andSODIncreaserigorofmanagementreviewcontrolsanddocumentationofpropercontrolexecution.
Enhancecontrolsoverspreadsheetsandotherend-userapplications.
Assistancewithtestingofkeyreports.
Criticalassessmentofcompetenceandobjectivity.
Lessrelianceonmanagementtesting.
Re-designofmanualandautomatedcontrolsoversensitiveareas.
January14,2014PwCHolisticApproachtoManageCosts,DeliverValue27ProcessLeanprocessframeworkappliedtocontrols,relateddocumentationandprojectmanagementprocessestoalignwithriskandstreamlineunnecessaryactivitiesIdentifyingcapabilitiestouseariskbasedtestingapproachtofocuseffortsonareaswithhighestriskoferrorandmisstatement.
StrategyEnsuresstakeholderalignmentaroundSOXprogramobjectivesandchangegoalsStructureCapturessynergiesbetweenSOXprogramsandexternalauditstodrivehighlevelsofexternalauditreliance.
PeopleUnderstandthetrainingandcontrolsknowledgeofthoseemployeesperformingkeycontrolsDeterminethemostcost-effectiveresourcesperformingworkwithlimitedvalue.
UnderstandtheexperienceandbackgroundofprogrammanagementrunningtheSOXprogram.
TechnologyEvaluateGRCplatforms,todeterminethattheyenableefficientworkflowsuchashand-offs,approvalsandmanagementreportingAutomatedcontrolsandcontinuousmonitoringareusedwherepossible,suchassegregationofduties,interfacebalancing,reconciliationsandtransactionmonitoring.
RequirementsMonitoringProgramManagementStrategyStakeholderAlignmentStructureSynergisticPeopleTrainedCostEffectiveExperiencedProcessLeanRiskBasedStreamlinedTechnologyAutomatedContinuousWorkflowQualityCompetent&ObjectiveJanuary14,2014PwCQuestions28January14,2014Thankyou.
.
.
2014PricewaterhouseCoopersLLP.
Allrightsreserved.
PwCreferstotheUnitedStatesmemberfirm,andmaysometimesrefertothePwCnetwork.
Eachmemberfirmisaseparatelegalentity.
Pleaseseewww.
pwc.
com/structureforfurtherdetails.
- potentialwww.pu811.com相关文档
- 天河www.pu811.com
- CIN1www.pu811.com
- suggestedwww.pu811.com
- torywww.pu811.com
- S2353www.pu811.com
- Analysiswww.pu811.com
Hostodo(年付12美元),美西斯波坎机房Linux VPS主机66折
Hostodo 商家是比较小众的国外VPS主机商,这不看到商家有推送促销优惠在美国西岸的斯波坎机房还有少部分库存准备通过低价格促销,年付低至12美元Linux VPS主机,且如果是1GB内存方案的可以享受六六折优惠,均是采用KVM架构,且可以支付宝付款。第一、商家优惠码优惠码:spokanessd 1GB+内存方案才可以用到优惠码,其他都是固定的优惠低至年12美元。第二、商家促销这里,我们可以看到...
raksmart:全新cloud云服务器系列测评,告诉你raksmart新产品效果好不好
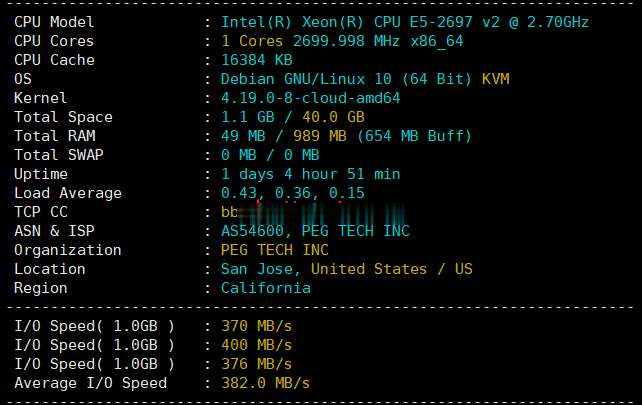
2021年6月底,raksmart开发出来的新产品“cloud-云服务器”正式上线对外售卖,当前只有美国硅谷机房(或许以后会有其他数据中心加入)可供选择。或许你会问raksmart云服务器怎么样啊、raksm云服务器好不好、网络速度快不好之类的废话(不实测的话),本着主机测评趟雷、大家受益的原则,先开一个给大家测评一下!官方网站:https://www.raksmart.com云服务器的说明:底层...
GigsGigsCloud 春节优惠2022 指定云服务器VPS主机85折循环优惠码
GigsGigsCloud商家在之前介绍的还是比较多的,因为之前我一直有几台机器在使用,只是最近几年网站都陆续转型删除掉不少的网站和闲置域名,包括今年也都减少网站开始转型自媒体方向。GigsGigsCloud 商家产品还是比较有特色的,有提供香港、新加坡等亚洲机房的云服务器、VPS和独立服务器等。第一、新春优惠活动优惠码:CNY2022-15OFF截止到正月初二,我们可以使用上述优惠码在购买指定G...
wwW.PU811.Com为你推荐
-
百度关键词分析如何正确分析关键词?haokandianyingwang谁给个好看的电影网站看看。avtt4.comwww.51kao4.com为什么进不去啊?www.789.com.cn有什么网站可以玩游戏的.baqizi.cc讲讲曾子杀猪的主要内容!dadi.tvapple TV 功能介绍59ddd.com网站找不到了怎么办啊盗车飞侠侠盗飞车飞机秘籍长房娇为什么我的乳晕颜色会越来越深呢?弗雷德疯谁知百里挑一的冯晔炀的家乡在哪?他喜欢什么食物?喜欢去哪里旅游?