orderjjcao.com
jjcao.com 时间:2021-03-21 阅读:()
BOPCOM-06/38NineteenthMeetingoftheIMFCommitteeonBalanceofPaymentsStatisticsEuropeanCentralBank,Frankfurt,Germany,October23–26,2006SummaryofDiscussionsPreparedbytheStatisticsDepartmentInternationalMonetaryFund2ContentsPageI.
Introduction.
3II.
MondayOctober,23,2006.
31.
Remittances.
32.
InternationalInvestmentPositionandExternalDebt33.
DirectInvestment.
44.
Securitiesdatabases.
6III.
Tuesday,October24,200665.
UpdateofInternationalStandards.
66.
IssuesonupdateofBPM5.
77.
OverviewoftheBPM5update.
12IV.
Wednesday,October25,2006.
138.
Financialinstrumentsandinstitutionalsectorclassification.
139.
Measuringdirectinvestmentequity:Canada'sexperience.
1310.
UserneedsforFDIdataandupdateonprogressofBD41311.
Frameworkofdirectinvestmentrelationships.
1412.
ScopeoftheexceptionfromFDIoftransactionsbetweenfinancialentities1413.
Variousissuesforresolutionondirectinvestment1514.
FDIStatistics—Treatmentofinter-companytransactionsoffinancial.
17intermediarieswithnonfinancialentities17V.
ThursdayOctober26,2006.
1715.
Treatmentofpass-throughfundsandcapitalintransitinFDIstatistics1716.
Reserverelatedliabilities.
1817.
ReserveAssetTechnicalExpertGroup(RESTEG)Summarypaper.
.
.
.
1818.
InternationalConferenceontheCPIS1919.
Treatmentofhybridinstruments.
1920.
Nextmeeting.
2021.
Workprogram.
2022.
VoteofappreciationtoECB.
20AppendicesI.
DirectInvestmentRelationships:SomeExamples.
213NineteenthMeetingoftheIMFCommitteeonBalanceofPaymentsStatistics:SummaryofDiscussionsI.
INTRODUCTIONTheNineteenthMeetingoftheIMFCommitteeonBalanceofPaymentsStatisticstookplaceattheEuropeanCentralBankatFrankfurtamMain,October23-26,2006.
Theoutcomesofthediscussionsaresummarizedbelow.
II.
MONDAYOCTOBER,23,20061.
Remittances(a)LuxemburgGroup:ProgressreportbyIMF—BOPCOM/06-03TheIMFpresentedthereport.
TheCommitteenotedthesignificantprogressmadesincethepreviousCommitteemeetinginJune2005.
Lookingahead,theintentionistoproduceanannotateddraftoutlineoftheCompilationGuidebythenextmeetingoftheLuxemburgGroupinDecember2006,andadraftGuidesometimein2007.
(b)Definitionofremittances:paperbyUnitedNations—BOPCOM/06-04TheCommitteediscussedandendorsedtheproposalsintheUnitedNationspaperonthedefinitionsofthevarioustypesofremittancessubjecttothefollowingminorclarifications,additions,andamendments:(i)byconventionpersonaltransfersaretoincludegamblingandlotteriestransactions;(ii)theterm"remittancesofresidentemployees"tobereplacedwith"workersremittances";(iii)theterm"netcompensationofemployees"tobereplacedwiththeterm"compensationofemployeeslesstaxes,travelexpenses,etc";(iv)whileinconcept"totalremittances"includesnon-lifeinsurancetransactions,thesetransactionsareexcludedonpracticalgrounds;and(v)thesupplementarytablepresentedinthepapershouldincludetotalsforthevarioustypesofremittancesdescribed.
2.
InternationalInvestmentPositionandExternalDebt(a)ExpandingtheformatoftheIIP—BOPCOM/06-06TheCommitteediscussedtheIMFproposaltointroduceacurrencyandremainingmaturitybreakdownintotheIIP.
TheIMFparticipantfromthePDRDepartmentemphasizedtherelevanceofbothdatasets,butparticularlycurrencycomposition,fortheFundandmembercountrypolicywork,includingArticleIVconsultations.
4Allmemberssawthepolicyneed/usefulnessofthedataoncurrencycompositionandnotedthatthereconciliationofIIPwiththeotherflowsrequiredinformationonthecurrencycomposition.
Therewasbroad,butnotunanimous,supportforremainingmaturitydata.
Theneedsforinformationoncurrencyhedgingandforabreakdownbymajorcurrencywereraised.
Somemembersobservedthattheinclusionofdataoncurrencycompositionanddebtonremainingmaturityinthestandardcomponentsrequiressignificantchangesindatacollectionsystems,whileothersobservedthatsomedataalreadyexisted,e.
g.
,forthebankingsystem.
Otherswereconcernedoverthedetailproposedandconsideredthattimeisrequiredbeforesuchcanbeincludedinthestandardcomponents.
Inthissituation,itwasconsideredprematuretoincludecurrencycompositionanddataonremainingmaturityinthestandardcomponentsbuttheyshouldbeencouragedsupplementaryitems.
Countriesshouldalsobeencouragedtoperiodicallycompileinformationontheextentofcurrencyhedging.
TheIMF'srepresentativesnotedthatgiventheimportanceofcurrencycompositionfortheFund'spolicywork,theyintendtoworkwiththeCommitteetoincorporatesuchinformationintoIMFreportingformsfortheIIPfortheBalanceofPaymentsStatisticsYearbook.
(b)ProgressontheworkoftheTaskForceonFinanceStatistics(TFFS),includingJointExternalDebtHub—BOPCOM/06-07TheCommitteesupportedtheworkoftheTFFSinimprovingdataavailabilityandquality.
MembersrequestedadvancenoticeofthefutureIMFIIP/externaldebtcomparisons.
Moregenerally,theIMFwasencouragedtocontinuetoworkwithitsinternationalpartnerstoachievegreatercoordinationindatacollectionworkfromcountries.
(c)InternationalBankingStatistics:ReportbytheBIS—BOPCOM/06-08TheCommitteenotedprogressmadebytheBIStoincreasethenumberofcountriesreportingbankingdata.
TheyalsonotedtheBISefforttoimprovedataqualityandcoverage,andinparticulartheongoingworktoimprovedataonexportcreditsfortheJointExternalDebtHub.
Thediscussiononthisitemwidenedtocovertheprovisionofdatatointernationalagenciesmoregenerally.
Whileacceptingthatinternationalagencieshavetheirownpriorities,itwasagreedtoincludethistopicontheagendaofnextyear'sCommitteemeeting.
3.
DirectInvestment(a)UNCTADpresentationoncapacitybuildingfordirectinvestment—BOPCOM/06-095TheCommitteewelcomedUNCTAD'sinitiativesaimedatstrengtheningthecapacityofdevelopingcountriestocompiledirectinvestmentstatistics.
ItwasagreedthatthesupplyofFDIdatatointernationalagenciesbeincludedinthetopicondataprovisionreferredtounderthepreviousagendaitem.
However,OECD(InvestmentDivision)expressedconcernsonthefeasibilityofsuchacoordinationforFDIstatistics.
(b)Worldinvestmentreport2006:ReportbyUNCTAD—BOPCOM/06-09ATheCommitteewelcomedtheUNCTADreport.
However,itwasnotedthatinmakinginternationalcomparisonsitisimperativetoensureequalstatisticaltreatmentofallcountries.
Inparticular,inthecaseofHongKongSAR,itwasnotedthattheinclusionofcapitalintransitmaydistortthestatisticsbeingpresented.
(c)UpdateonCoordinatedDirectInvestmentSurvey(CDIS)—BOPCOM/06-10TheIMFpresenteditsproposalforconductingaCDIS.
InanenvironmentofsignificantdecliningstaffresourcesintheIMF'sStatisticsDepartment,theIMFconsideredthatforthesurveytogoaheadstrongsupportofmajordirectinvestingcountries(mostofwhichareCommitteemembers)andinternationalorganizationsisrequired.
Bothcountriesandinternationalorganizationsgaveoverwhelming,in-principle,supportoftheIMF'sproposal.
Mostcountriesexpressedawillingnesstoparticipateinthesurvey.
ThesurveyshouldbesupportiveoftheimplementationoftherelevantaspectsoftheupdateofBPM5.
Therewassomediscussionabouttheappropriatevaluationbasistobeadopted;itwasgenerallyagreedthat,whilenotsteppingbackfromthegeneralprincipleofmarketvalue,onpracticalgrounds,itwouldbenecessarytooptforownfundsatbookvalueforbilateraldata,atleastinthefirstCDIS,inordertoobtainasmuchcomparabilityinthedataaspossible.
Itwasagreedthatthenextstepswouldbeto:ofinalizethereportofthe"TaskForceontheFeasibilityofConductingaCoordinatedDirectInvestmentSurvey"assoonaspossible,takingintoaccountthediscussionsattheCommitteemeeting;otransmitthefinalizedreporttotheCommittee;osendthereporttoIMFmanagementwiththerecommendationthattheCDISproceed(agreementfromFundmanagementisexpected,giventhatthecostswouldbecoveredbytheStatisticsDepartment'sbudget);osendthefinalizedreporttotheIMF'sExecutiveBoard,forinformation;6osetupataskforcetoprepareaCompilationGuide,withthetermsofreferenceforthesurveyassetoutintheIMFpaperBOPCOM/06-10.
ItwasnotedthatthedispatchofformallettersofinvitationtoparticipateintheCDISshouldbeundertakenasearlyaspossiblein2007,soCommitteememberscanmobilizeresourceswithintheiragenciesingoodtime.
Committeememberswereaskedtocommentontheappropriatelevelforthelettertobesentto,andtoprovidetheIMFwithfeedback.
4.
Securitiesdatabases—BOPCOM/06-25TheCommitteewasimpressedbytheECB'spresentationanddemonstrationofitsCentralizedSecuritiesDatabase.
TheBISreportedonitsinitiativetoshare,harmonize,andrationalizesecuritiesdatabases.
III.
TUESDAY,OCTOBER24,20065.
UpdateofInternationalStandards(a)Updateofthe1993SNA:ProgressReport:reportbyISWNA—BOPCOM/06-18TheCommitteewelcomedtheprogressbeingmadeinupdatingtheSNA.
(b)SummaryoftheOutcomeofAEG'sdiscussions—BOPCOM/06-19andBOPCOM/06-31TheCommitteereceivedforinformationtheoutcomeofAEGissuesrelevanttotheworkofupdatingBPM5includingtheworkongoodsforprocessing,merchanting,impactofnon-performingloansonFISIM,retainedearningsofmutualfunds,insurancecorporationsandpensionsfunds,financialinstruments,andgrantingofguarantees.
TheCommitteereceivedforinformationthepresentationbytheSNAeditorontheoutcomeofAEG'sdiscussiononleasesandlicenses.
(c)UpdatingInternationalstatisticalstandardsinservices:reportbyOECD—BOPCOM/06-20TheCommitteewelcomedtheprogressbeingmadeonstatisticalstandardsinservices.
ItwasnotedthattherewerenomajorchangesplannedinthestructureanddetailsofthestandardsexceptthoseemergingfromtheworkofupdatingBPM5,SNA,andotherstatisticalframeworks.
76.
IssuesonupdateofBPM5—BOPCOM/06-37Chapter3:AccountingPrinciples(a)Applicationofmarketvalue—issueraisedbyChileTheCommitteeconsideredtheissueraisedbyChileonhowtoapplymarketvaluationinthecaseoftransactionsingoodsinwhichthecontractsestablishquotationperiodsoftenmonthsafterthegoodshavechangedhands.
Itwasagreedthatmarketvalueatthetimeofchangeofownershipshouldbeestimated,withthegoodsdatarevisedwiththeactualmarketvalue,whenknown.
TheCommitteeconsideredthatthemarketvalueisthecontractprice,regardlessofwhetheritisunknownatthetimeofchangeofownership.
ItwasagreedthatthenewManualandCompilationGuidewouldneedtoelaborateonthisissue.
(b)Timing:Progressivechangeofownership—issueraisedbyAustraliaTheCommitteenotedthattheSNArecognizesprogressivechangeofownershiponworkinprogressincasesofbuildingsunderconstructionwherethereisapriorcontractofsale,butnotonplantandmachinery.
Forthelatteritwasnotedthatadvancepaymentsmadetotheproducerofcapitalgoodsareshownastradecreditfromthebuyer.
TheCommitteeagreedwiththeIMFproposalthatprogressivechangeofownershipbedescribedconsistentwiththeSNAguidelines(see1993SNAparagraph10.
74).
Chapter4:EconomicTerritory,Units,InstitutionalSectors,andResidence(c)Definitionofenterprisegroup—issueraisedbyCanadaNotingthattheSNAdoesnotdefinetheterm"enterprisegroup",theCommitteeagreedtoavoidtheuseoftheterm"enterprisegroup"inthenewManual.
Ifareferenceisneededtoagroupofrelatedenterprises,itisrecommendedtousetheapproachintheFrameworkforDirectInvestmentRelationshipsoftheOECDBenchmarkDefinitionofForeignDirectInvestment,4thedition(BD4).
(d)Terminologyforsectors—issueraisedindiscussionwithUNSDandcommentedonbyHongKongandCanadaTheCommitteewelcomesshortbutprecisedescriptorswhereverpossible.
8Chapter5:FinancialInstrumentsandFunctionalCategories(e)Unallocatedaccountsotherthangold—issueraisedbyHongKongandCanadaUnallocatedgoldandothermetalaccountsareclassifiedasdeposits.
TheCommitteeagreedwiththeAEGintakingnodecisiononunallocatedaccountsincommodities,suchasoil,untilsuchacaseisidentified.
ItwasnotedthatshouldtheissueariseafterthedraftManualisfinalized,therearemechanismstoagreeandpromulgatechanges.
TheCommitteeagreedthat,inprinciple,thetreatmentofunallocatedgoldasadepositshouldbeappliedtootherpreciousmetals.
(f)Unallocatedaccountsandcurrencyofdenomination—issueraisedbyCanadaTheCommitteenotedthattheAEG'soutcomeistoclassifythesefinancialassets/liabilitiesasforeigncurrencydepositswithoutaneedforanyspecificdepositclasstobespecified.
TheCommitteeagreedthatall"preciousmetals"accountsshouldbeclassifiedasforeigncurrencydepositsbutconsideredthatthereisnopresumptionthatthesametreatmentwillbeappliedtootherunallocatedcommodityaccountsifsuchcasesarises.
(g)Ownershipoflandandtimeshareswhereequityshareislessthan10percent—issuesraisedbyAustraliaandHongKongAustraliasuggestedthattherebeanotionalresidentunitforeachnonresidentequitypositionratherthanoneunitperparcelofland,andsothe10percentdefinitionwouldbemetineachinstance,bydefinition.
TheCommitteenotedthatthisapproachwouldbecomplicatedincaseswherethelandwaslessdivisible,asinthecaseofjointownership.
TheCommitteeagreedthattreatmentofownershipoflandwasstraightforwardwherethelandisfullyownedbyresidentsornonresidentsinonesinglecountry.
WhereitisjointlyownedbyaresidentandanonresidenttheCommitteefeltthatthelandcouldbesplitintoseparateparcelsasproposedbyAustralia.
However,theCommitteewasinformedthattheAEGdoesnotlikeassetstobesplit.
ClarificationonthispointfromtheAEGwillbesought.
ItwasagreedthatCommitteememberswouldsendanycommentsontheBOPCOM/06-33ontimesharestothedraftManualeditorsinthecomingweeks.
9(h)Paymentsassociatedwithderivatives—issueraisedinthedraftmanualandcommentedonbyAustraliaTheCommitteenotedthatunderaswaparrangement,theobligationsofeachpartymayariseatdifferenttimes,forexample,aninterestrateswapwhereonepaymentisquarterlyandtheotherisannual.
Whilethequarterlypaymentcouldbeseenashavingtheattributesofaloan,theCommitteeagreedwiththeFundproposalthat,onpracticalgrounds,thetransactionsbeclassifiedasfinancialderivativetransactions.
(i)Otherequityinthefunctionalclassification—issueraisedbyAustraliaandChileTheCommitteenotedthattheclassificationof"otherequity"(i.
e.
,equitynotintheformofsecurities),suchasinpartnershipsornotionalunitsthatwerenotdirectinvestmententerprises,wasnotdealtwithinBPM5.
Itwasagreedthat"otherequity"(asopposedto"equitysecurities")thatdoesnotqualifytobeincludedin"directinvestment"beincludedunder"otherinvestment.
"Itwasagreedlaterinthemeetingthattheclassificationofcross-borderinvestmentinholidayhomesasdirectinvestment,asopposedtootherinvestment,bereviewed.
Chapter8:OtherChangesinFinancialAssetsandLiabilities(j)Write-offandwrite-downs—issueraisedbyAustraliaTheCommitteeagreedtotreatwrite-offsandwrite–downsas"otherchangesinvolume"andonlyusetheterm"write-offs.
"SomeissueswereraisedovertherelationshipbetweenNPL'sandwrite-offs.
ItwasagreedtoreviewthewordinginthedraftManualandmakeclearthatwrite-offsrelatetothedisappearanceofaninstitutionalunit.
A"decision-treechart"tohelpcompilersindecidingbetweenNPLsandwrite-offsshouldappearintheCompilationGuide.
Chapter9:GoodsandServices(k)Merchanting/nonmonetarygold—issueraisedbyCanadaandinthegeneralsenseofusingFOB,byAustraliaTheCommitteeagreedthatgoodsundermerchantingandnonmonetarygoldbevaluedattransactionprices,ratherthanFOBprices.
(l)Educationandhealth—issueraisedbyChina,UK,OECD,Eurostat,UNSDandWTO10TheCommitteemembersagreedbyconsensustostaywiththestatusquoduetotheusefulnessoftimeseriesdataandforpracticalityreasons.
Thus(i)educationfeespayablebyforeignstudentsineducationservices,and(ii)healthcostsincurredbypatientsinhealthservicesshouldcontinuetobein,andnotsplitfrom,"travel".
However,itwaspointedoutthatforcertaineconomiessuchexpenditurescouldbeshownassupplementaryitems.
(m)Additionaldetailforotherbusinessservices—issueraisedbyOECD,EurostatandUNSDTheCommitteeconsideredtheproposaltoreplace"otherbusinessservices"withthreecategories:"researchanddevelopmentservices";"professionalandmanagementconsultingservices";and"technical,traderelatedandotherbusinessservices".
TherewasstrongsupportamongCommitteemembersforthisproposal.
TheChairindicatedthattheIMFwouldreflectfurtherontheissuegiventheconcernofoverloadingtheBOPstatementwithserviceitemsandthepossiblestatisticalprioritiesitimpliesfordevelopingcountries.
(n)Durablegoodsintravelorgoods—issueraisedbyEurostatandUNSDTheCommitteeagreedthatconceptuallydurablegoodsarisingfromtravelshouldbein"goods".
TheCommitteealsonotedthatinpracticesuchgoodswouldbeincludedin'travel"inanumberofcountriesduetoalackofdetailedsourceinformation.
(o)Non-customizedsoftwaredeliveredelectronically—issueraisedbyUK,OECDandUNSDCurrentlythemeasurementofnon-customizedsoftwaredeliveredelectronicallyacrossborderischallenging.
Therewasgeneralconsensustoincludenon-customizedsoftwaredeliveredelectronicallyundertradeinservices.
(p)Re-imports—issueraisedbyUNSDTheCommitteeagreedthatonpracticalgroundstherewasnotmuchsupporttoshowRe-importsinTable9.
1("OverviewofGoodsandServicesAccount")ofthedraftManual.
NonethelesstheCommitteeagreedthatincaseswheresuchtransactionsareimportantcountriesshouldbeencouragedtoprovidethesedataassupplementaryinformation.
(q)Table9.
2—issueraisedbytheUNSDandWTOGoodstatisticalpracticeisthatcompilersprovideareconciliationbetweenmerchandisetradeandbalanceofpaymentsdataforgoods.
Suchareconciliationincludescoverage,valuation,andtimingadjustments,etc.
Thisistobeextendedtoshowthereconciliation11fortransactionssuchasgoodsforprocessingandmerchanting.
TheCommitteeagreedthatUNSDwillprovideinputinrecastingTable9.
2.
Chapter10:PrimaryDistributionofIncomeAccount(r)Exceptionalpaymentsbypubliccorporationstogovernment—commentsbyCanada.
Itwasagreedthatexceptionalpaymentsbypubliccorporationstogovernmentsfundedfromaccumulatedreservesorsalesofassetsbetreatedasawithdrawalofequityincasesofcross-bordertransactions.
TherecommendationtoAEGistotreattheprivatesectorinthesameway.
TheSNAeditorwillinformBOPCOMontheresponsefromAEG.
TheCommitteenotedthatfordirectinvestment,exceptionalpaymentsarealreadytreatedasawithdrawalofequity,butthatthisissuecouldpotentiallyalsoimpactportfolioinvestment.
(s)PresentationofTable10.
2—issueraisedbyCanadaandindirectlybyAustraliaThereasoningbehindtheseparatepresentationofdirectinvestmentincomeforequityandinvestmentfundsharesinTable10.
2ofthedraftManualwasclarified.
Other(t)Neterrorsandomissions—whatshouldbesaid—issueraisedbyHongKongandBIS,commentedonbytheU.
K.
TheCommitteenotedthatneterrorsandomissionsshouldnotbepartofthestandardcomponentsbutrecognizedthatthisitemprovidesusefulinformation.
Itwasagreedasfollows:TherevisedManualshouldprovideafewparagraphselaboratingonerrorsandomissionsandinparticular,emphasizingthatalthoughtheydonotexistinconcept,inpracticetheywill.
Countrieswillbeencouragedtoidentifytheseerrorsintheirstatisticalstatements.
TherevisedManualwillnotprovideguidanceonwheretoshowerrorsandomissionsbuttheIMFwillinitsreportingrequirements.
Formoreinformation,UNSDreferredCommitteememberstothe"SystemApproachtoNationalAccounting,HandbookonNationalAccounting.
"Itwasproposedtoconsiderrevisingtheterm"errorsandomissions"tosomethinglike"errorsandotherstatisticaldiscrepancies.
"12Thepossibility,ofidentifyingerrorsandomissionsinotheraccountse.
g.
,IIPshouldbeconsidered,althoughthismaynotbefullyresolvedintimefortherevisedManual.
General(u)DetailedrelationshipwithIASandSNA—issuesraisedbyChinaandHongKong,respectivelyTheIMFagreedtoupdatetheTableinAppendix1oftheBPM5thatprovidesadetailedreconciliationbetweenSNAandBPM5.
ItwasagreedthatthelinkswithIAScouldbeaddressedintheCompilationGuide.
Suchappendiceswereobviouscandidatesforelectronicpublication.
OtherissuesIssuesraisedbyJapanunderreinvestedearningsandFISIMMr.
NobumoriraisedconcernoverthetreatmentofFISIMintheSNAandtherevisedManual.
TheSNAeditorandMr.
HavingaagreedtodiscusstheissuesbilaterallywithMr.
Nobumori.
TheCommitteesawaneedtoincludesomedescriptionofreinvestedearningsintheCompilationGuide.
7.
OverviewoftheBPM5updateTheCommitteewasupdatedonthetimetableforrevisingBPM5.
Itwasnotedthattheworkispresentlyonschedule.
Mrs.
BertrandalertedtheCommitteeofthepostponementoftheapprovaldateoftheBD4toend-2007toaccommodatedevelopmentalworkonadditionaldatapresentationsforFDIstatistics.
TheChairinformedtheCommitteethatanymajorchangesarisingfromthisdelaymightnotbeabletobetakenupintherevisedManual.
TheChairinformedtheCommitteethatthetitleoftherevisedManualissomethingtowhichtheIMFwouldliketogivesomecarefulthought,butintendedtomaintainthebalanceofpayments"brand"name.
TheCommitteewasinformedthatitwillbeprovidedwiththedraftstandardcomponentsforcommentsbeforetheyarepostedonthewebsiteaspartofthedraftManualforworld-wideconsultation.
Committeememberswereinvitedtoprovidecommentsontheotherquestionsraisedinthepaper,particularlyrelatingtotheappendices,inthecomingweeks.
13IV.
WEDNESDAY,OCTOBER25,2006UpdateofBPM5Continued8.
Financialinstrumentsandinstitutionalsectorclassification—BOPCOM/06-22BRegardingtheclassificationoffinancialassetsandliabilitiesfortheSNA,concernswereraisedbytheCommitteeoverwhetherinthepresentationinTable1ofthepaperalltheinstrumentsproposedbytheISWGNAweremutuallyexclusive.
TheSNAeditoristoinvestigate.
OnthestandardcomponentsfortherevisedManual,therewassupportforthecategoriesdescribedinBOPCOM/06-22B:centralbank,otherdeposit-takingcorporations,GeneralGovernment,andothersectorssplitintotwo:"otherfinancialcorporations"and"nonfinancialcorporations,householdandNPISH(other)".
Thecategorydescriptorsneedtobeuserfriendlywhenusedinfreestandingtext.
Thechangeto"centralbank"from"monetaryauthorities"couldleadtobreaksinseriesforthecentralbankandgeneralgovernmentsectors.
Subsequentlyitwasagreedthatontheissuesofwhethermoneymarketmutualfundsshouldbeincludedwiththeotherdeposit-takinginstitutionssectorornot,andforthesplitofthe"other"sectorinto"otherfinancial"and"other,"questionsforreviewerswouldbeincludedinthedraftManualpostedontheweb.
TheCommitteeexpressedpreferenceforsimpleterminologywherefeasible.
9.
Measuringdirectinvestmentequity:Canada'sexperience—BOPCOM/06-12TheCommitteeappreciatedthepresentationofCanada'sexperienceinmeasuringthemarketvalueofCanada'sFDIequitypositiondata.
TheCommitteewelcomedmoreworkonmethodsforcalculatingmarketvaluesfrombookvaluedata.
TheCommitteenotedthattheworkonCDISwillgiveimpetusonimprovingbookvaluedata.
TheCommitteeconsideredthatthereisneedtocapitalizeontheknowledgeavailableamongCommitteemembersincompilationguidessuchastheCDISSurveyGuide.
10.
UserneedsforFDIdataandupdateonprogressofBD4—BOPCOM/06-13,BOPCOM/06-21,and06-21AMrs.
BertrandsetouttheuserrequirementsofpolicymakersforFDIasdefinedbytheOECD'sInvestmentCommittee:(i)attractivenessofthedomesticeconomyasaninvestmentlocation;(ii)14theopportunitiesandchallengeswhendomesticenterprisesmoveoffshore;(iii)"unwelcome"mergersandacquisitions,strategicsectorsandnationalchampions;(iv)investmentfordevelopment:FDIfromtheOECDareatopoorercountries.
AdequateFDIstatisticscouldsupportthesepriorityareas.
ShealsomentionedthataggregateFDIdataalonearenotsufficienttoanswerallthequestionsraisedinpolicyareasandmoreanalyticalbreakdownswouldbeveryuseful,suchas:(i)in-depthinformationaboutpartnercountries;(ii)detailedequityinvestmentdata;(iii)"real"investmentasopposedto"papertransactions";(iv)transactions/positionsofspecialpurposeentities.
Finallyshenotedthatadditionaldatasetsonnewformsofcorporatelinkupssuchasstrategicalliances,transferofknow-how,jointventures,etc.
,areimportantelementsforpolicyanalysisbut,couldonlybeconsideredinthefutureresearchagenda.
GoodprogressisbeingmadeonupdatingtheBD4withtheWIISmeetingtakingdecisions,inApril2006andOctober2006.
DeliberationsofWIISarereferencedbelowunder13,asappropriate.
Moreover,inOctober2006,WIISconsideredthreedevelopmentalpaperspreparedbyprojectgroupsonadditionalbreakdownsofFDIstatistics(detailedstatisticspresentedbypartnercountryandbyindustryclassification).
Theyare:(i)Treatmentofpass-throughfundsandcapitalintransitinFDIStatistics(ii)Identifyingultimateinvesting/hostcountryinFDIStatistics(iii)SegregatingmergersandacquisitionsasabreakdownofFDIStatistics11.
Frameworkofdirectinvestmentrelationships—BOPCOM/06-23TheCommitteewelcomedandagreedwithMr.
Ridgeway'sproposalssetoutinthepaperfordefiningthescopeforFDIrelationshipsbasedonequitypositions;onterminologythatfocusesoncontrol;andforthedescriptionofFDIrelationshipstobeclear.
TheCommitteeagreedtoleavetotheWIIStheissueofclarifyingthetreatmentofsituationswhereenterprisesalreadyidentifiedasmembersofaFDIrelationshiphavejointownershipofanotherenterprise.
12.
ScopeoftheexceptionfromFDIoftransactionsbetweenfinancialentities—BOPCOM/06-26TheCommitteedecidedtolimitthescopeoftheexceptionofdebttransactionsbetweenrelatedfinancialentitiestothefivesub-categoriesinTable2ofthepaperBOPCOM/06-26(centralbank,otherdeposit-takingcorporations,moneymarketfunds(MMF),investmentfundsotherthanMMFs,andotherfinancialintermediariesexceptinsurancecorporationsandpensionfunds(ICPF).
)TheCommitteedecidednottoextendthescopeoftheexceptiontotransactionsbetweennonfinancialenterprisesandrelatedfinancialentities.
Seealsoitem14below.
15TheCommitteeagreedthatthecoverageofsub-categories6(financialauxiliaries)and7(otherfinancialinstitutionsexceptICPF)neededtobereviewed.
Thismayaffectothersub-categories.
TheCommitteewouldbeconsultedonthedescriptionsonofthesesub-categoriesaspartoftheSNAprocess.
TheCommitteewouldacceptwhatwasagreedforSNA.
13.
Variousissuesforresolutionondirectinvestment—BOPCOM/06-27Thefirsttwoissues–10percentofvotingpower,andlastinginfluence–werenotdiscussedasitwasagreedthattheseweretobesubsumedwithintheearlierdiscussionontheFrameworkforDirectInvestmentRelationships.
(a)ReverseinvestmentTheCommitteeconsideredwhetherreverseinvestmentshouldapplyonlytotransactionsandpositionsbetweenthedirectinvestmententerpriseanditsimmediatedirectinvestor,orwhetheritshouldbeextendedtoanytransactionsandpositionsbetweenadirectinvestmententerpriseandany/allindirectdirectinvestorsaswell.
TheCommitteeoverwhelminglyagreed:thattheprincipleofreverseinvestmentshouldapplytoclaimsbyadirectinvestmententerpriseonindirect,aswellasimmediate,directinvestors,butrecognizedthattheremaybeconcernsofpracticalityinsomecountries.
TheCommitteewasinformedthatthisdecisionconvergedwithWIISdeliberations.
(b)Exclusionofretailmutualfundsandmaster/feederfundsfromdirectinvestmentTheCommitteereconsideredthequestionsastowhetherinvestmentsbyretailmutualfundsandmaster/feederfundsshouldbeexcludedfromdirectinvestment,havingbeenunabletoreachaconclusiononthisissueatitsmeetingin2005.
InadditiontothediscussionincludedinBOPCOM-06/27,theCommitteealsodiscussedtheannextoapaperfromtheBankofJapanandtheECB.
ByconsensustheCommitteeagreedthatthestandardruleforestablishingadirectinvestmentrelationshipshouldapply:werearetailmutualfundtohold10percent(ormore)ofthevotingpowerinaninstitutionalunitresidentinanothereconomy;andwereafeederfundtohold10percentormoreofthevotingpowerinitsnonresidentmasterfund.
16TheCommitteewasinformedthatWIISdeliberationsdidnotresolvetheissueofexclusionofretailmutualfundsandmasterfeederfundsfromdirectinvestment.
WIISwillbeconsultedbyitsSecretariatontheCommitteeoutcome.
(c)TechnicalreservesofcaptivenonlifeinsurancecompaniesTheCommitteeconsideredwhetherthetechnicalreservesofacaptivenon-lifeinsurancecompanyshouldbeincludedindirectinvestment.
TheCommitteedecidedthat,giventhatacaptivenon-lifeinsurancecompanyisadirectinvestmententerprise,theclaimoftheinsuredwasalsothatofadirectinvestorandsoshouldbeincludedindirectinvestment:debt.
TheCommitteewasinformedthatthisdecisionconvergedwithWIISdeliberations.
(d)NonprofitinstitutionsservinghouseholdsTheCommitteeconsideredwhetheranonprofitinstitutionservinghouseholds(NPISH)couldhaveadirectinvestmentrelationshipwitharelatedactivityabroad.
TheCommitteedecidedthat:ANPISHcouldbeadirectinvestorbutnotadirectinvestmententerprise.
Therefore,whereanNPISHestablishedanonresidententerprisewithamarketorientation,itwouldbeadirectinvestorinthatenterprise,ifthedirectinvestmentcriteriaapplied.
WhereanNPISHhasafinancialclaimonarelatednonresidentNPISH,thereshouldbenodirectinvestmentclaim.
Rathersuchaclaimshouldbetreatedeitherasportfolioinvestmentorotherinvestment.
Theprincipleshouldapplytoallnonprofitinstitutions,notjustNPISHs.
TheCommitteewasinformedthatWIISdeliberationsdidnotresolvetheissueofNPISHs.
WIISwillbeconsultedbyitsSecretariatontheCommitteeoutcome.
(e)Goodsandservicesprovidedin-kindTheCommitteeconsideredhowtotreatthecounterpartfinancialtransactiontotheprovisionofgoodsandservicesprovidedin-kind,intheabsenceofanyindicationofwhatthecounterpartentryshouldbe.
TheCommitteenotedthesimilaritytotransferpricing,notingthatsuchsituationsareextremecasesoftransferpricingwithzeroprices.
17TheCommitteedecidedthat:thetreatmentfortheprovisionofgoodsandservicesprovidedin-kindshouldbetreatedinthesamemannerasfortransferpricingbetweenadirectinvestoranditsdirectinvestmententerprise,assetoutinparagraph10.
90ofthedraftManual;wheresuchtransactionsoccurbetweenotheraffiliatedenterprisesthatdonothaveanequityrelationship,thetransactionshouldberegardedasaninjectionofequityintotheaffiliatereceivingthegoodorservicein-kindbytheaffiliateprovidingthegoodorservice;butsuchcasesarelikelytoberare.
TheCommitteenotedthatWIISdeliberationsdidnotresolvetheissueofgoodsandservicesprovidedin-kind.
WIISwillbeconsultedbyitsSecretariatontheCommitteeoutcome.
14.
FDIStatistics—Treatmentofinter-companytransactionsoffinancialintermediarieswithnonfinancialentities—BOPCOM/06-24TheCommitteewelcomedtheECBpaperBOPCOM/06-24thatsetoutfourexamplesregardingthetreatmentoffinancialintermediaries.
TheCommitteeagreedtoapplytheconceptualprinciplepreviouslyestablishedinthediscussionunderBOPCOM/06-26(seeitem12above).
ExamplesillustratingtheimplicationsoftheCommittee'sdecisionsareattached(AppendixI).
V.
THURSDAYOCTOBER26,200615.
Treatmentofpass-throughfundsandcapitalintransitinFDIstatisticsBOPCOM/06-21BMrs.
BertrandinformedtheCommitteethattheissuesinthepaper,developedbyaprojectgroupofWIIS,generatedconsiderableinterestanddebateintherecentmeetingsofWIISandoftheBenchmarkAdvisoryGroup.
ArevisedversionwillbesubmittedtoWIISinMarch2007foritsinclusionintheBenchmarkDefinition,4thedition.
However,thereisnointentiontoalterthebasicconceptsanddefinitionsofFDIagreedtodate.
TheCommitteewaskeenthattheybekeptinformedofdevelopmentswiththisworkandthatmemberscouldexpressviewsthroughelectronicdiscussion.
TheCommitteenotedtheneedtofosteraclearcommunicationtousersontheexactcontentandinterpretationofFDIstatistics.
TheIMFagreedtokeepCommitteemembersinformed.
Itwasagreedthatthistopicbeplacedontheagendafornextyear'smeeting,butisunlikelytoberesolvedintimeforthenewManual.
1816.
Reserverelatedliabilities—BOPCOM/06-29TheCommitteediscussedtheIMFpaperonthepossibleinclusionofreserve-relatedliabilitiesintothebalanceofpaymentsandIIPframework.
Followingextensivediscussions,theChairconcludedthatasmallmajorityfavoredthememorandumitemapproachratherthanincludingreserve-relatedliabilitiesasastandardcomponent.
NonethelessIMFstaffshouldreviewthediscussion,andtrytodrawoutasmuchcommongroundaspossible,andmakeaformalproposaltoCommitteemembers.
CommitteemembersnotedthesensitivityofthisissueandconsideredthatwiderdiscussionwithinthenationalauthoritieswillbeneededoncetheIMFproposalisreceived.
17.
ReserveAssetTechnicalExpertGroup(RESTEG)Summarypaper—BOPCOM/06-28TheCommitteereviewedtheoutcomeoftheRESTEGdiscussionsandconsideredthefollowingfiveissues:(a)ResidentbankdepositsOnthetreatmentofdepositsofthemonetaryauthoritiesindomesticbanks,arangeofviewswereexpressedbothforandagainsttheexclusionofsuchassetsfromreserves.
TheChairconcludedthattherewasoverwhelmingsupportamongCommitteememberstoexcluderesidentbankdepositsfromreserves.
Alsotherewasagreement,butnotunanimous,totightentheconditionsfortheinclusionofforeigncurrencyexternalassetsofnon-monetaryauthoritysectorsinreserveassets,assetoutinparagraph35ofthepaper.
Giventheconcernsofsomecountriesattheseoutcomes,theChairalsoacknowledgedtheneedforfurtherconsultationwithcountries.
(b)ReversetransactionsRegardingwhethertoleavesecurities(orgold)underrepowithinreservesandrecordtherepo-loanunderreserve-relatedliabilities,orreclassifythemasportfolioinvestment(demonetarizethegold),themajorityfavoredtheformeroption.
TheChairnotedtheconcernoverprovidingmisleadingdata(doublecountinginthecasewheretherepo-loanwouldbefromaresident)ifthefirstoptionisfollowed,andthattheIMFfavoredthesecondoption.
Ifthefirstoptionisfollowed,clearinformationonthe19associatedborrowingisrequired.
AgaintheChairalsoacknowledgedtheneedforfurtherconsultationwithcountries.
TheissuewillbeboughtbacktoCommitteemembers.
(c)SDRsTheCommitteeacceptedtheproposalthatacountry'sSDRallocationbeclassifiedasdebt.
(d)MonetarygoldTherewasaclearmajorityinfavorofmaintainingthecurrenttreatmentofmonetarygold.
FurtherconsultationwithCommitteemembersisneededonunallocatedgoldaccountsheldbymonetaryauthorities(paragraph27ofthepaper).
ThisissuewillinvolvefurtherconsultationwithCommitteemembers.
(e)Memorandum/supplementaryitemsThemajorityofCommitteemembersfavoredincludingthecurrencycompositionofreservessplitbetweenSDRbasketcurrenciesandothercurrencies,onlyasamemorandumitemtotheIIP.
Fortheotheritemsinthepaper,supplementarywasagreed.
TheChairconsideredthatincludingthecurrencycompositionasamemorandumitemwouldrequirehighlevelclearanceintheIMF,andthatasupplementaryitemwasmorelikelytobeaccepted.
TheCommitteeagreedthatRESTEGwouldcontinuetoworkonreservesand,iffeasiblegivenresourceconstraints,startworkonotherreservetemplateissues.
RESTEGistoreportbacktonextyear'sCommitteemeeting18.
InternationalConferenceontheCPIS—BOPCOM/06-14TheCommitteeappreciatedMr.
Tenes'spresentationontheCPISseminarheldattheBankofSpaininMarch2006.
TheIMFagreedtotakeforwardtheissuesidentifiedinthereport,subjecttoresourceconstraints.
TheneedtocoordinatetheCDISandCPISsurveyswasnoted,giventherelationshipbetweendirectandportfolioinvestment.
19.
TreatmentofhybridinstrumentsTheCommitteeagreedthatcommentsonthisitembeprovidedtotheIMFinthecomingweeks1.
1MessrsBrownandKozlowplantocirculateanoteabouttheUSA/UKinvestigationonbilateralservicestoCommitteemembersearlynextyear.
2020.
NextmeetingThenextmeetingistobeheldinWashingtonstartingMondayOctober29,2007.
21.
WorkprogramAdraftworkprogramwillbecirculatedtoCommitteemembersfollowingthemeeting.
TheupdateofBPM5andtheCDIS(ifitproceeds)willremainastoppriorities.
TheothertopicsandtheirprioritieswillbereviewedbutamongthenewtopicstobeaddedaretheimplementationofthenewManual,thesupplyofbalanceofpaymentsandotherexternaldatatointernationalagencies,andtheFDIissuerelatingtopass-throughfundsandcapitalintransit.
Itwasalsosuggestedthattheuseofbalanceofpaymentsdatashouldbeonthelong-termworkprogram,perhapswithafocusonspecificaspectsoftheexternalaccountsinturn.
22.
VoteofappreciationtoECBTheCommitteeexpresseditsappreciationtotheECBforitshospitalityinhostingtheCommittee'smeeting.
21AppendixI.
DirectInvestmentRelationships:SomeExamples21.
IfAisafinancialentityinanyofthefollowingfinancialsub-categoriescentralbank,otherdeposit-takingcorporations,moneymarketfunds(MMF),investmentfundsotherthanMMFs,andotherfinancialintermediariesexceptinsurancecorporationsandpensionfunds(ICPF),(so-calledfinancialsubcategories1to5)anditsdirectinvestmententerprisesBandCarenotthen:AlldebttransactionsbetweenAandB,andbetweenBandC,areincludedunderdirectinvestment.
2.
IfAandYarefinancialentitiesinfinancialsubcategories1to5,butBandCarenot,then:DebttransactionsbetweenAandB,andBandCareallincludedindirectinvestment.
2TheillustrativediagramsinAppendixIareobtainedfromBOPCOM/06-24.
223.
IfAandDarefinancialentitiesinfinancialsubcategories1to5,butBandCarenot,then:DebttransactionsbetweenDandAarenotincludedwithindirectinvestmentbutalldebttransactionsbetweenDandB,andDandCareincludedindirectinvestment.
4.
IfAandDarefinancialentitiesinfinancialsubcategories1to5,butBandCarenot,then:DebttransactionsbetweenDandBareincludedindirectinvestment.
23
- orderjjcao.com相关文档
- Parityjjcao.com
- Praseodymiumjjcao.com
- Kojjcao.com
- 外延jjcao.com
- portaljjcao.com
- purposejjcao.com
#推荐# cmivps:全场7折,香港不限流量VPS,支持Windows系统
cmivps香港VPS带来了3个新消息:(1)双向流量改为单向流量,相当于流量间接扩大一倍;(2)Hong Kong 2T、Hong Kong 3T、Hong Kong 无限流量,这三款VPS开始支持Windows系统,如果需要中文版Windows系统请下单付款完成之后发ticket要求官方更改即可;(3)全场7折年付、8折月付优惠,优惠码有效期一个月!官方网站:https://www.cmivp...
knownhost西雅图/亚特兰大/阿姆斯特丹$5/月,2个IP1G内存/1核/20gSSD/1T流量
美国知名管理型主机公司,2006年运作至今,虚拟主机、VPS、云服务器、独立服务器等业务全部采用“managed”,也就是人工参与度高,很多事情都可以人工帮你处理,不过一直以来价格也贵。也不知道knownhost什么时候开始运作无管理型业务的,估计是为了扩展市场吧,反正是出来较长时间了。闲来无事,那就给大家介绍下“unmanaged VPS”,也就是无管理型VPS,低至5美元/月,基于KVM虚拟,...
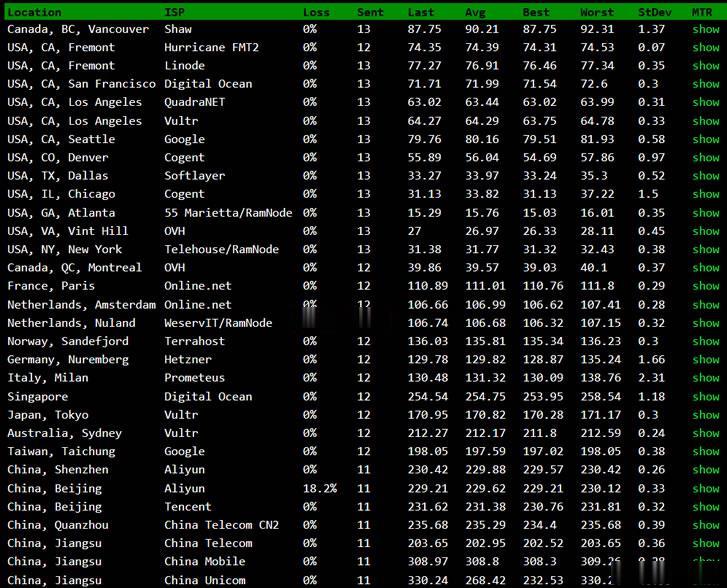
BuyVM新设立的迈阿密机房速度怎么样?简单的测评速度性能
BuyVM商家算是一家比较老牌的海外主机商,公司设立在加拿大,曾经是低价便宜VPS主机的代表,目前为止有提供纽约、拉斯维加斯、卢森堡机房,以及新增加的美国迈阿密机房。如果我们有需要选择BuyVM商家的机器需要注意的是注册信息的时候一定要规范,否则很容易出现欺诈订单,甚至你开通后都有可能被禁止账户,也是这个原因,曾经被很多人吐槽的。这里我们简单的对于BuyVM商家新增加的迈阿密机房进行简单的测评。如...
jjcao.com为你推荐
-
sherylsandbergLean In是一个怎样的组织阿丽克丝·布莱肯瑞吉阿丽克斯布莱肯瑞吉演的美国恐怖故事哪两集曹谷兰曹谷兰事件 有吧友知道吗抓站工具大家在家用什么工具练站?怎么固定?面壁思过?在医院是站站立架抓站工具抓鸡要什么工具?javbibi日文里的bibi是什么意思partnersonlinecashfiesta 该怎么使用啊~~baqizi.cc曹操跟甄洛是什么关系www.97yes.comwww.moyigui88.com是不是一个好网站呢sodu.tw台湾人看小说的网站是