英文版江苏省涉外税收优惠政策指导书(英文版)
省涉外税收优惠政策指南(英文版)Preferential Tax Pol icy Guidance For Enterprises withForeign Investment and Foreign Enterprises
Preferential Tax Pol icy Guidance For Enterprises with Foreign Investment and ForeignEnterprises
Preferential Turnover Tax Pol icy
Items shal l be exempt from VAT
Preferential tax pol icies for agricultural means of production
Preferential VAT pol icies for part of the products made through multiple uti l ization ofresources
Preferential consumption taxpol icies for scented soap and vehicle tire
Preferential Tax Pol icies of EFIs and FEs Income Tax
Taxation at reduced rates
Taxation on enterprise income at 15%
Taxation on enterprise income at 24%
Fixed term tax reductions and exemptions
Two year’s exemptions adjoining three year’s 50%reduction
Other fixed term tax reductionsand exemptions
Tax refund on reinvestment
Comprehensive regional tax incentives
Other tax incentives
Withholding tax
Profit (Dividend)
Interest
Royalty
Rentals
Benefits Received from Transfer of Property
Preferential Turnover Tax Pol icy
I . Items shal l be exempt from VAT:
1 .Self-produced agricultural products sold by agricultural producers;
2.Contraceptive medicines and devices;
3.Antique books;
4. Instruments and equipment imported which is directly used in scientific research,
experiment and education,
5. Materials and equipment imported from foreign government and internationalorganizations as assistance free of charge;
6.Equipment and machinery required to be imported under contract processing,contractassembly and compensation trade,
7.Articles imported directly by organizations for the disabled for special use by thedisabled;
8.Sale of goods which have been used by thesel lers.
I I .Preferential tax pol icies for agricultural means of production:
1 .Fol lowing goods are exempted from VAT:i . Forage, including large amount unitary forage, mixed forage, compound feed,concentrated forage,i i .Agricultural fi lms;i i i .Certain kind of chemical ferti l izer;iv. Agricultural pesticides within designated scope produced and sold by pesticidefacto ries,v.Seeds, seedl ing, chemical ferti l izer, pesticide and agriculture machinery marketed bywhole sales and retai l .
I I I .Preferential VAT pol icies for part of the products made through multiple uti l ization ofresources:
1 .The construction bui lding materials,which combined with content of 30%coal gangue,stone coal ,powdered coal and furnace slag(not including blast furnace wet slag),should
be exempted from VAT.
2.The gold extracted from l iguid waste and offscum should be exempted from VAT.IV.Preferential consumption taxpol icies for low pol lution emission vehicles:
Beginning from Jan. 1st 2000, cars, cross-country vehicles and mini-buses with lowpol lution emission wi l l be grantedwith 30%reduction of the consumption tax.
V.Preferential consumption taxpol icies for scented soap and vehicle tire:
1 .Beginning from Jan. 1st,2001 , scented soap l isted in the taxation item of “Skin&HairCare Product”would be exempted from consumption tax.
2.Beginning from Jan. 1st,2001, “radial tire” l isted in the vehicle tire taxation item wi l l beexempted from consumption tax.The renovated tire wi l l be free from consumption tax.The consumption tax on the rest of the tires wi l l be levied at 10%.
Part I I
PreferentialTax Pol icies of EFIs and FE Income Tax
I .Taxation at reduced rates
1 .Taxation on enterprise income at 15%
A 15%Enterprise Income Tax rate shal l apply to those EFIs located in Special EconomicZones, Foreign Enterprises (hereinafter referred to as FE)with establ ishments or fixedplaces in Special Economic Zones engaged in production and business operation,as wel las those EFI of production nature which have establ ishments in Economic and
Technological DevelopmentZones.
The Enterprise Income Taxon EFI in Coastal Economic Open Zones, in old urban districtsof cities where the Special Economic Zones or the Economic and TechnologicalDevelopment Zones are located,or other places specified by the State Counci l ,may beimposed at the reduced rate of 15%, provided that the operation activities of thoseenterprises are centered on power and energy, transportation and communication, harborand port, dock and wharf, and other projects inspired by the State Counci l .The specificrules shal l bestipulated by the State Counci l .
(Section 1 ,3 of Article 7, the Tax Law)
The appl ication of 15%reduced Enterprise Income Tax rate mentioned in paragraph 1 ofarticle 7,Tax Law, is l imited to incomes procured by enterprises from production andbusiness operation in the respective areas specified in paragraph 1 ,article 7.
(Section 1 of Article 71 , the Detai led Rules)
The Special Economic Zones mentioned in paragraph 1 ,article 7, refers to those specialareas sanctioned by the State Counci l including Shenzhen,Zhuhai ,Shantou,Xiamen,Hainan Island; the Economic Technological Development Zones refers to areas set up incoastal port cities which are under the approval of the State Counci l .
(Article 69, the Detai led Rules)
The enterprises that may enjoy 15%of the reduced income tax rate, as stipulated inparagraph 3,article 7 of the Income Tax Law,are mainly l isted below:
1 .EFIs of production nature which have establ ishments in the old urban districts of thecities where the Coastal Economic Open Zones,Special EconomicZones, the Economic
Technological Development Zones are located, and which are engaged in the fol lowingp rojects:a.Technology intensive or knowledge intensive projects;b. Projects with foreign investment of$30 mi l l ion or more, and with a long period ofrecovery of investment;c.Projects engaged in energy, transportation and communication,port constructions
2.Foreign-Chinese Equity Joint Ventures engaged in the construction of ports and docks;
3. Foreign banks, Foreign-Chinese Joint Invested Banks and other financial institutionslocated in Special Economic Zones or other places approved by the State Counci l ,withthe capital provided by foreign investors or operation funds acquired from theheadquartersof foreign banks total ing no less than$10 mi l l ion;and at the same time withan operation period of ten yearsor more;
4.EFIs of production nature setup in Pudong NewArea,Shanghai ;and any EFI engagedin energy exploitation and transportation construction projects such as airports, ports,rai lways, highways,and electricity power stations;
5.The accredited high technological EFIs set up in New and High-Technology IndustrialDevelopment Zones identified by the State Counci l ;or the accredited new technologicalEFI situated in Beijing NewTechnology Development and Experiment Zones;
6.Any EFI establ ished in otherplaces specified by the State counci l and engaged in suchprojects as encouraged by the State.
Any EFI which meet the criteria set in item 1 of this Article shal l , upon the appl ication’shaving been endorsed by the State Administration of Taxation, be el igible for a reduced
income tax rate of 15%.
(Article 73, the Detai led Rules)
2.Taxation on enterprise income at24%
Any EFI of a production nature situated in the urban district of the cities which boast aCoastal Economic Open Zone,a Special Economic Zoneoran Economic and TechnologyDevelopment Zone shal l be el igible for a reduced income tax rate of 24%.
(Section 2 of Article 7, the Tax Law)
The tax objectives enjoying a 24%rate,as stated in paragraph 2,Article 7 of the IncomeLaw,shal l only be l imited to income derived from production or business operation withinthe areas specified in paragraph 2,Article 7 of the Income Law.
(Section 2 of Article 71 , the Detai led Rules)
The‘Coastal Economic Open Zones’stated in paragraph 2,Article 7 of the Income Law,refers to any coastal city,county,or district sanctioned by the State Counci l .
(Article 70, the Detai led Rules)
I I .Fixed term tax reductions and exemptions
1 .Two year’s exemptions adjoining three year’s 50%reduction
Any EFI of a production nature intended to conduct business in China for at least 10 yearsshal l , from its first profits-making year, be entitled to two year’s income tax exemptionadjoining three year’s 50%reduction.However,such exemptions and reductions shal l notapply tothose EFI engaged in the exploitation of such natural resourcesasoi l , natural gas,rare and precious metals, since tax pol icies of these l ines shal l be formulated separatelyby the State Counci l . In addition, it is compulsory for those EFIs which have already
enjoyed tax exemptions and reductions to spit out the exact amount if their actualoperation period is no more than 10 years.
(Section 1 of Article 8, the Tax Law)
The tax incentives specified in paragraph 1 ,Article 8 of the Tax Law shal l not be put onthose EFIs engaged in the exploitation of such natural resources as petroleum, naturalgas, rare and precious metals, unless and unti l other related regulations are made by theState Counci l .
(Article 78, the Detai led Rules)
Any EFI which meet the qual ifications of paragraph 1 ,Article 8 of the Tax Law,which mayenjoy taxexemptions or concessions,shal l report its l ine,main products,operation period,etc to the local competent taxauthorities for approval ,otherwise its tax incentives shal l bedenied.
(Section 2 of Article 74, the Detai led Rules)
2.Otherfixed term tax reductions and exemptions
Any relevant regulation issued by the State Counci l prior to the effectiveness of this Lawwi l l sti l l hold to the extent that the relevant regulation has provided more attractive taxtreatment as of a longer period of exemption or reduction for those EFIs which undertakeproduction and construction projects l ike energy, communications, harbor, docks etc,orhas provided such preferential tax treatment as exemptions and reductions for those EFIsengaged in non-production nature projects.
(Section 2 of Article 8, the Tax Law)
‘Any relevant regulation issued by the State Counci l prior to the effectiveness of this Law’
- 英文版江苏省涉外税收优惠政策指导书(英文版)相关文档
- 担保中小企业税收优惠政策辅导手册2012年5月
- 合同合同优惠系统需求规范标准
- 企业所得税企业所得税优惠政策汇总
- 营业税企业政策性搬迁或处置收入企业所得税优惠政策解读
- 减免税《企业所得税优惠政策备案管理暂行办法(试行)》
- virmach优惠码比亚迪秦昆明有优惠政策吗
RAKsmart裸机云/云服务器/VPS全场7折,独立服务器限量秒杀$30/月起
适逢中国农历新年,RAKsmart也发布了2月促销活动,裸机云、云服务器、VPS主机全场7折优惠,新用户注册送10美元,独立服务器每天限量秒杀最低30.62美元/月起,美国洛杉矶/圣何塞、日本、香港站群服务器大量补货,1-10Gbps大带宽、高IO等特色服务器抄底价格,机器可选大陆优化、国际BGP、精品网及CN2等线路,感兴趣的朋友可以持续关注下。裸机云新品7折,秒杀产品5台/天优惠码:Bare-...

#推荐# cmivps:全场7折,香港不限流量VPS,支持Windows系统
cmivps香港VPS带来了3个新消息:(1)双向流量改为单向流量,相当于流量间接扩大一倍;(2)Hong Kong 2T、Hong Kong 3T、Hong Kong 无限流量,这三款VPS开始支持Windows系统,如果需要中文版Windows系统请下单付款完成之后发ticket要求官方更改即可;(3)全场7折年付、8折月付优惠,优惠码有效期一个月!官方网站:https://www.cmivp...
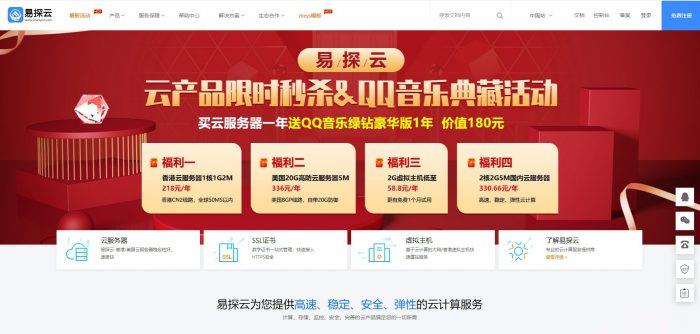
易探云香港云服务器价格多少钱1个月/1年?
易探云怎么样?易探云是目前国内少数优质的香港云服务器服务商家,目前推出多个香港机房的香港云服务器,有新界、九龙、沙田、葵湾等机房,还提供CN2、BGP及CN2三网直连香港云服务器。近年来,许多企业外贸出海会选择香港云服务器来部署自己的外贸网站,使得越来越多的用户会选择易探云作为网站服务提供平台。今天,云服务器网(yuntue.com)小编来谈谈易探云和易探云服务器怎么样?具体香港云服务器多少钱1个...
-
投资者适当性客户端系统深圳市富满电子集团股份有限公司重庆网通重庆网通上网资费目前是多少? 小区宽带接入类型的xp如何关闭445端口请大家帮帮忙,怎样关闭135和445端口?ipad如何上网ipad如何允许app使用网络ipad如何上网iPad怎么上网?请高手指点ipad连不上wifiiPad 连不上Wifi,显示无互联网连接css下拉菜单CSS如何把下拉菜单改为上拉菜单tcpip上的netbiostcp 协议里的 netbios . 在哪,找不到联通版iphone4s联通版iPhone4s 用联通3G卡好还是移动的好