differencedrewrite规则
rewrite规则 时间:2021-01-12 阅读:()
Titlestata.
comarimapostestimation—PostestimationtoolsforarimaDescriptionSyntaxforpredictMenuforpredictOptionsforpredictRemarksandexamplesReferenceAlsoseeDescriptionThefollowingpostestimationcommandsareofspecialinterestafterarima:CommandDescriptionestatacplotestimateautocorrelationsandautocovariancesestatarootscheckstabilityconditionofestimatesirfcreateandanalyzeIRFspsdensityestimatethespectraldensityThefollowingstandardpostestimationcommandsarealsoavailable:CommandDescriptionestaticAkaike'sandSchwarz'sBayesianinformationcriteria(AICandBIC)estatsummarizesummarystatisticsfortheestimationsampleestatvcevariance–covariancematrixoftheestimators(VCE)estimatescatalogingestimationresultsforecastdynamicforecastsandsimulationslincompointestimates,standarderrors,testing,andinferenceforlinearcombinationsofcoefcientslrtestlikelihood-ratiotestmarginsmarginalmeans,predictivemargins,marginaleffects,andaveragemarginaleffectsmarginsplotgraphtheresultsfrommargins(proleplots,interactionplots,etc.
)nlcompointestimates,standarderrors,testing,andinferencefornonlinearcombinationsofcoefcientspredictpredictions,residuals,inuencestatistics,andotherdiagnosticmeasurespredictnlpointestimates,standarderrors,testing,andinferenceforgeneralizedpredictionstestWaldtestsofsimpleandcompositelinearhypothesestestnlWaldtestsofnonlinearhypotheses12arimapostestimation—PostestimationtoolsforarimaSyntaxforpredictpredicttypenewvarifin,statisticoptionsstatisticDescriptionMainxbpredictedvaluesformeanequation—thedifferencedseries;thedefaultstdpstandarderrorofthelinearpredictionypredictedvaluesforthemeanequationiny—theundifferencedseriesmsemeansquarederrorofthepredictedvaluesresidualsresidualsorpredictedinnovationsyresidualsresidualsorpredictedinnovationsiny,reversinganytime-seriesoperatorsThesestatisticsareavailablebothinandoutofsample;typepredict.
.
.
ife(sample).
.
.
ifwantedonlyfortheestimationsample.
PredictionsarenotavailableforconditionalARIMAmodelsttopaneldata.
optionsDescriptionOptionsdynamic(timeconstant)howtohandlethelagsofytt0(timeconstant)setstartingpointfortherecursionstotimeconstantstructuralcalculateconsideringthestructuralcomponentonlytimeconstantisa#oratimeliteral,suchastd(1jan1995)ortq(1995q1);seeConvenientlytypingSIFvaluesin[D]datetime.
MenuforpredictStatistics>Postestimation>Predictions,residuals,etc.
OptionsforpredictFivestatisticscanbecomputedusingpredictafterarima:thepredictionsfromthemodel(thedefaultalsogivenbyxb),thepredictionsafterreversinganytime-seriesoperatorsappliedtothedependentvariable(y),theMSEofxb(mse),thepredictionsofresidualsorinnovations(residual),andthepredictedresidualsorinnovationsintermsofy(yresiduals).
GiventhedynamicnatureoftheARMAcomponentandbecausethedependentvariablemightbedifferenced,thereareotherwaysofcomputingeach.
Wecanuseallthedataonthedependentvariablethatisavailablerightuptothetimeofeachprediction(thedefault,whichisoftencalledaone-stepprediction),orwecanusethedatauptoaparticulartime,afterwhichthepredictedvalueofthedependentvariableisusedrecursivelytomakelaterpredictions(dynamic()).
Eitherway,wecanconsiderorignoretheARMAdisturbancecomponent(thecomponentisconsideredbydefaultandisignoredifyouspecifystructural).
Allcalculationscanbemadeinoroutofsample.
arimapostestimation—Postestimationtoolsforarima3Mainxb,thedefault,calculatesthepredictionsfromthemodel.
IfD.
depvaristhedependentvariable,thesepredictionsareofD.
depvarandnotofdepvaritself.
stdpcalculatesthestandarderrorofthelinearpredictionxb.
stdpdoesnotincludethevariationarisingfromthedisturbanceequation;usemsetocalculatestandarderrorsandcondencebandsaroundthepredictedvalues.
yspeciesthatpredictionsofdepvarbemade,evenifthemodelwasspeciedintermsof,say,D.
depvar.
msecalculatestheMSEofthepredictions.
residualscalculatestheresiduals.
Ifnootheroptionsarespecied,thesearethepredictedinnovationst;thatis,theyincludetheARMAcomponent.
Ifstructuralisspecied,thesearetheresidualstfromthestructuralequation;seestructuralbelow.
yresidualscalculatestheresidualsintermsofdepvar,evenifthemodelwasspeciedintermsof,say,D.
depvar.
Aswithresiduals,theyresidualsarecomputedfromthemodel,includinganyARMAcomponent.
Ifstructuralisspecied,anyARMAcomponentisignored,andyresidualsaretheresidualsfromthestructuralequation;seestructuralbelow.
Optionsdynamic(timeconstant)specieshowlagsofytinthemodelaretobehandled.
Ifdynamic()isnotspecied,actualvaluesareusedeverywherethatlaggedvaluesofytappearinthemodeltoproduceone-step-aheadforecasts.
dynamic(timeconstant)producesdynamic(alsoknownasrecursive)forecasts.
timeconstantspecieswhentheforecastistoswitchfromonestepaheadtodynamic.
Indynamicforecasts,referencestoytevaluatetothepredictionofytforallperiodsatoraftertimeconstant;theyevaluatetotheactualvalueofytforallpriorperiods.
Forexample,dynamic(10)wouldcalculatepredictionsinwhichanyreferencetoytwitht00otherwisemeaningthatpredictnewvar,xbcalculatespredictionsbyusingthemetricofthedependentvariable.
Inthisexample,thedependentvariablerepresentedchangesinln(wpit),andsothepredictionsarelikewiseforchangesinthatvariable.
Ifweinsteaduse.
predicty,yStatacomputesytasyt=xbt+ln(wpit1)sothatytrepresentsthepredictedlevelsofln(wpit).
Ingeneral,predictnewvar,ywillreverseanytime-seriesoperatorsappliedtothedependentvariableduringestimation.
IfwewanttoignoretheARMAerrorcomponentswhenmakingpredictions,weusethestructuraloption,.
predictxbs,xbstructuralwhichgeneratesxbst=β0becausetherearenoregressorsinthismodel,and.
predictys,ystructuralgeneratesyst=β0+ln(wpit1)arimapostestimation—Postestimationtoolsforarima5Example1:DynamicforecastsAnattractivefeatureofthearimacommandistheabilitytomakedynamicforecasts.
Inexample4of[TS]arima,wetthemodelconsumpt=β0+β1m2t+tt=ρt1+θt1+tFirst,weretthemodelbyusingdataupthroughtherstquarterof1978,andthenwewillevaluatetheone-step-aheadanddynamicforecasts.
.
usehttp://www.
stata-press.
com/data/r13/friedman2.
keepiftimechi2=0.
0000OPGDS4.
lnm1Coef.
Std.
Err.
zP>|z|[95%Conf.
Interval]ARMAarL1.
.
3551862.
05030117.
060.
000.
2565979.
4537745L4.
-.
3275808.
0594953-5.
510.
000-.
4441895-.
210972/sigma.
0112678.
000488223.
080.
000.
0103109.
0122246Note:Thetestofthevarianceagainstzeroisonesided,andthetwo-sidedconfidenceintervalistruncatedatzero.
.
irfcreatenonseasonal,set(myirf)step(30)(filemyirf.
irfcreated)(filemyirf.
irfnowactive)(filemyirf.
irfupdated)WetthefollowingseasonalARIMAmodel(1ρ1L)(1ρ4,1L4)4lnm1t=tThecodebelowtsthisnonseasonalARIMAmodelandsavesasetofIRFresultstotheactiveIRFle,whichismyirf.
irf.
.
arimaDS4.
lnm1,ar(1)mar(1,4)noconstantnologARIMAregressionSample:1961q2-2008q2Numberofobs=189Waldchi2(2)=119.
78Loglikelihood=588.
6689Prob>chi2=0.
0000OPGDS4.
lnm1Coef.
Std.
Err.
zP>|z|[95%Conf.
Interval]ARMAarL1.
.
489277.
05380339.
090.
000.
3838245.
5947296ARMA4arL1.
-.
4688653.
0601248-7.
800.
000-.
5867076-.
3510229/sigma.
0107075.
000474722.
560.
000.
0097771.
0116379Note:Thetestofthevarianceagainstzeroisonesided,andthetwo-sidedconfidenceintervalistruncatedatzero.
.
irfcreateseasonal,step(30)(filemyirf.
irfupdated)8arimapostestimation—PostestimationtoolsforarimaWenowhavetwosetsofIRFresultsinthelemyirf.
irf.
WecangraphbothIRFfunctionssidebysidebycallingirfgraph.
.
irfgraphirfThetrajectoriesoftheIRFfunctionsaresimilar:eachgureshowsthatashocktolnm1causesatemporaryoscillationinlnm1thatdiesoutafterabout15timeperiods.
Thisbehaviorischaracteristicofshort-memoryprocesses.
See[TS]psdensityforanintroductiontoestimatingspectraldensitiesusingtheparametersestimatedbyarima.
ReferenceEnders,W.
2004.
AppliedEconometricTimeSeries.
2nded.
NewYork:Wiley.
Alsosee[TS]arima—ARIMA,ARMAX,andotherdynamicregressionmodels[TS]estatacplot—Plotparametricautocorrelationandautocovariancefunctions[TS]estataroots—CheckthestabilityconditionofARIMAestimates[TS]irf—CreateandanalyzeIRFs,dynamic-multiplierfunctions,andFEVDs[TS]psdensity—Parametricspectraldensityestimationafterarima,arma,anducm[U]20Estimationandpostestimationcommands
- differencedrewrite规则相关文档
- seinrewrite规则
- Akrewrite规则
- Application-centric
- 银行rewrite规则
- Dueckrewrite规则
- Pizirewrite规则
Raksmart VPS主机如何设置取消自动续费
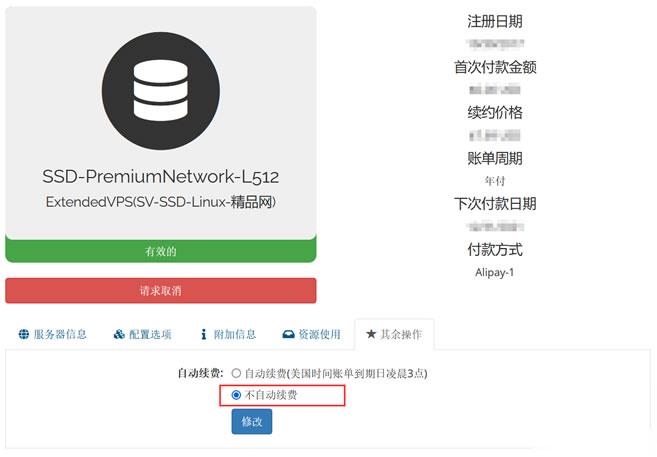
今天有看到Raksmart账户中有一台VPS主机即将到期,这台机器之前是用来测试评测使用的。这里有不打算续费,这不面对万一导致被自动续费忘记,所以我还是取消自动续费设置。如果我们也有类似的问题,这里就演示截图设置Raksmart取消自动续费。这里我们可以看到上图,在对应VPS主机的【其余操作】中可以看到默认已经是不自动续费,所以我们也不要担心被自动续费的。当然,如果有被自动续费,我们确实不想续费的...
wordpress专业外贸建站主题 WordPress专业外贸企业网站搭建模版
WordPress专业外贸企业网站搭建模版,特色专业外贸企业风格 + 自适应网站开发设计 通用流行的外贸企业网站模块 + 更好的SEO搜索优化和收录 自定义多模块的产品展示功能 + 高效实用的后台自定义模块设置!采用标准的HTML5+CSS3语言开发,兼容当下的各种主流浏览器: IE 6+(以及类似360、遨游等基于IE内核的)、Firefox、Google Chrome、Safari、Opera...
CloudCone月付$48,MC机房可小时付费
CloudCone商家在前面的文章中也有多次介绍,他们家的VPS主机还是蛮有特点的,和我们熟悉的DO、Linode、VuLTR商家很相似可以采用小时时间计费,如果我们不满意且不需要可以删除机器,这样就不扣费,如果希望用的时候再开通。唯独比较吐槽的就是他们家的产品太过于单一,一来是只有云服务器,而且是机房就唯一的MC机房。CloudCone 这次四周年促销活动期间,商家有新增独立服务器业务。同样的C...
rewrite规则为你推荐
-
服务器租用游戏服务器租用多少钱一年?海外主机租用怎么选择优质的国外服务器租用商!.net虚拟主机虚拟主机如何设置net版本?虚拟主机代理请问虚拟主机的代理和虚拟主机分销有什么区别?分销的主机是不是可以把主机分给多个用户使用?我用的ResellerClub代理!!国内ip代理求一些国内《ip代理》地址大全个人虚拟主机个人网站该购买什么类型虚拟主机?jsp虚拟空间JSP虚拟目录及虚拟路径的配置方法网站空间免备案免备案网站空间哪个好天津虚拟主机在天津哪个地方能买到较好的价格又实惠还可以送货上门的虚拟主机!云南虚拟主机大家觉得云南天成科技服务器租用给力吗?